OptionSpace.ai
The Edge

The Edge Is in the Details

Every week, options traders make decisions based on vol surfaces that are quietly wrong. Not visibly wrong, but wrong in the systematic, compounding way that gradually explains poor backtest results, unexpected hedge ratios, and strategies that work in theory and fail in practice.

The comparison below uses a European Black–Scholes benchmark with a flat interest rate, zero dividends and zero borrow. It includes risk-free carry: F = S erT. It does not model discrete dividends or American early exercise, or infer financing and borrow from the options market.

Here's what that looks like, and why it matters.

One number, and why it matters

The simplest test of whether a vol surface is correct: at the same strike, a call and a put should have the same implied volatility. For European options that is put-call parity. American options break parity because of early exercise, but the same test still holds: an American pricer given the right forward, the right dividends and the right exercise boundary returns the same implied vol from both sides.

A call/put IV discrepancy can expose differences in forward, dividend or exercise assumptions, as well as quote quality. Those assumptions also affect the Greeks derived from the model.

Below, each chart compares the same market quotes under two sets of pricing assumptions: the simplified benchmark on the left and OptionSpace on the right. These are model comparisons, not measurements of a specific vendor’s outputs.

Left panel: simplified European benchmark

Uses spot grown at a flat 4.58% rate, with zero dividends and borrow. Risk-free carry is included; discrete dividends, implied borrow, the rate term structure and American early exercise are not.

Right Panel: OptionSpace

Implies the forward with our American pricer, uses implied rate curves from the options market, and models dividends as discrete cash payments. American vol pricing with early exercise.

Blue dotsCall implied vols, one per strike.
Red dotsPut implied vols, at the same strikes. The fitted vol curve runs through both.
The key testAt any given strike, a call and a put should have the same implied volatility. A discrepancy calls for checking forward, dividend and exercise assumptions, together with quote quality.
Vertical barsThe bid/ask spread on that quote, in vol terms. Where a bar runs the full height of the panel, the option is past its early-exercise boundary and no implied vol exists at all; every vol below a threshold reproduces the price, so we decline to invent one.

All charts below use SPY options data from 10 November 2025 , a typical Monday with no unusual market events. The same patterns appear on any trading day and for any American-exercise stock.

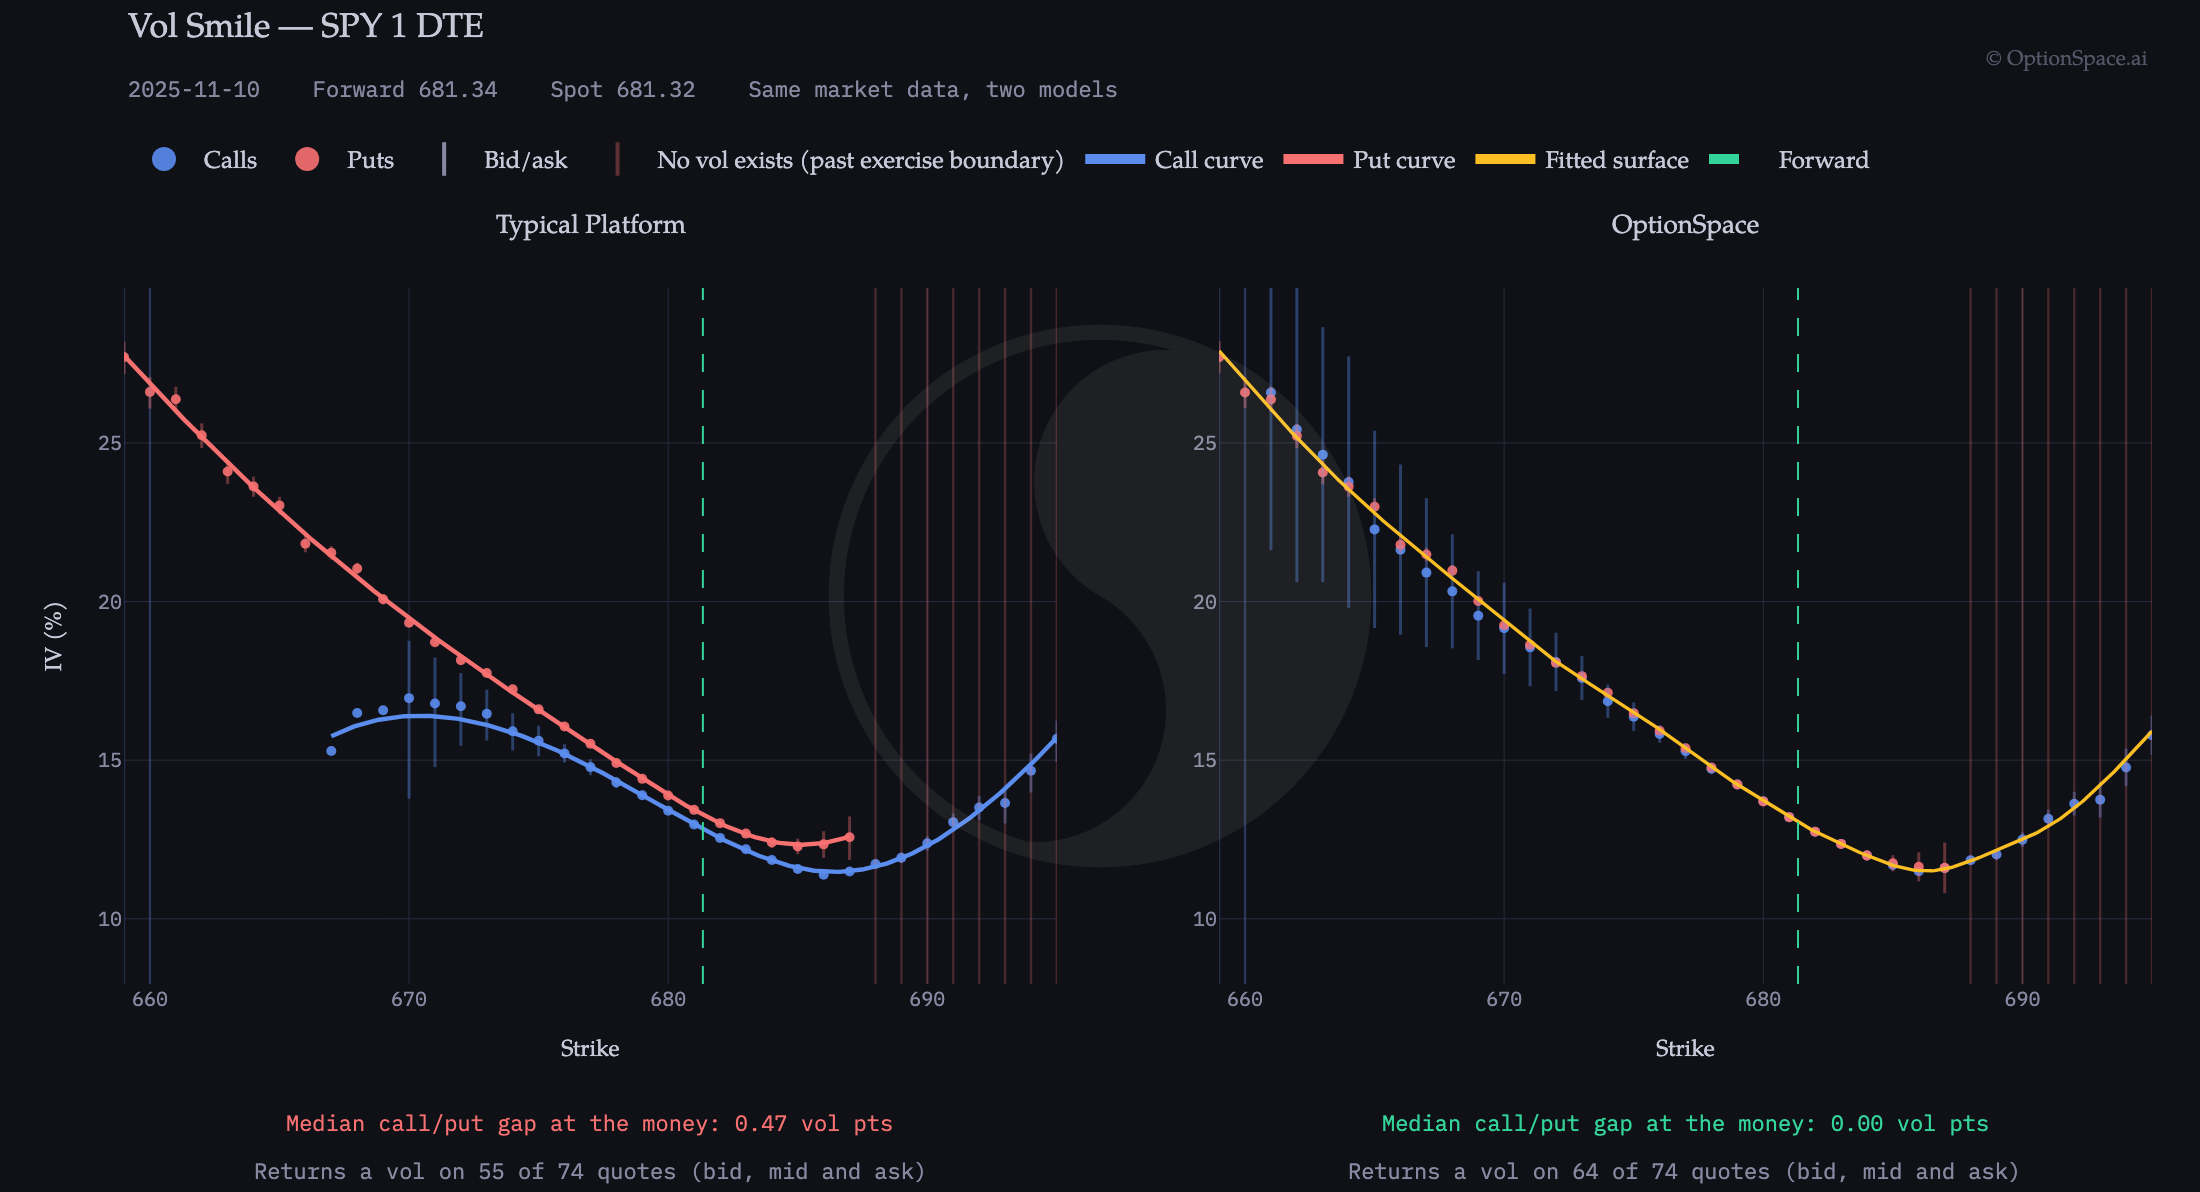
0.47vp Call/put gap at 1 day. Even overnight, spot is not the forward.
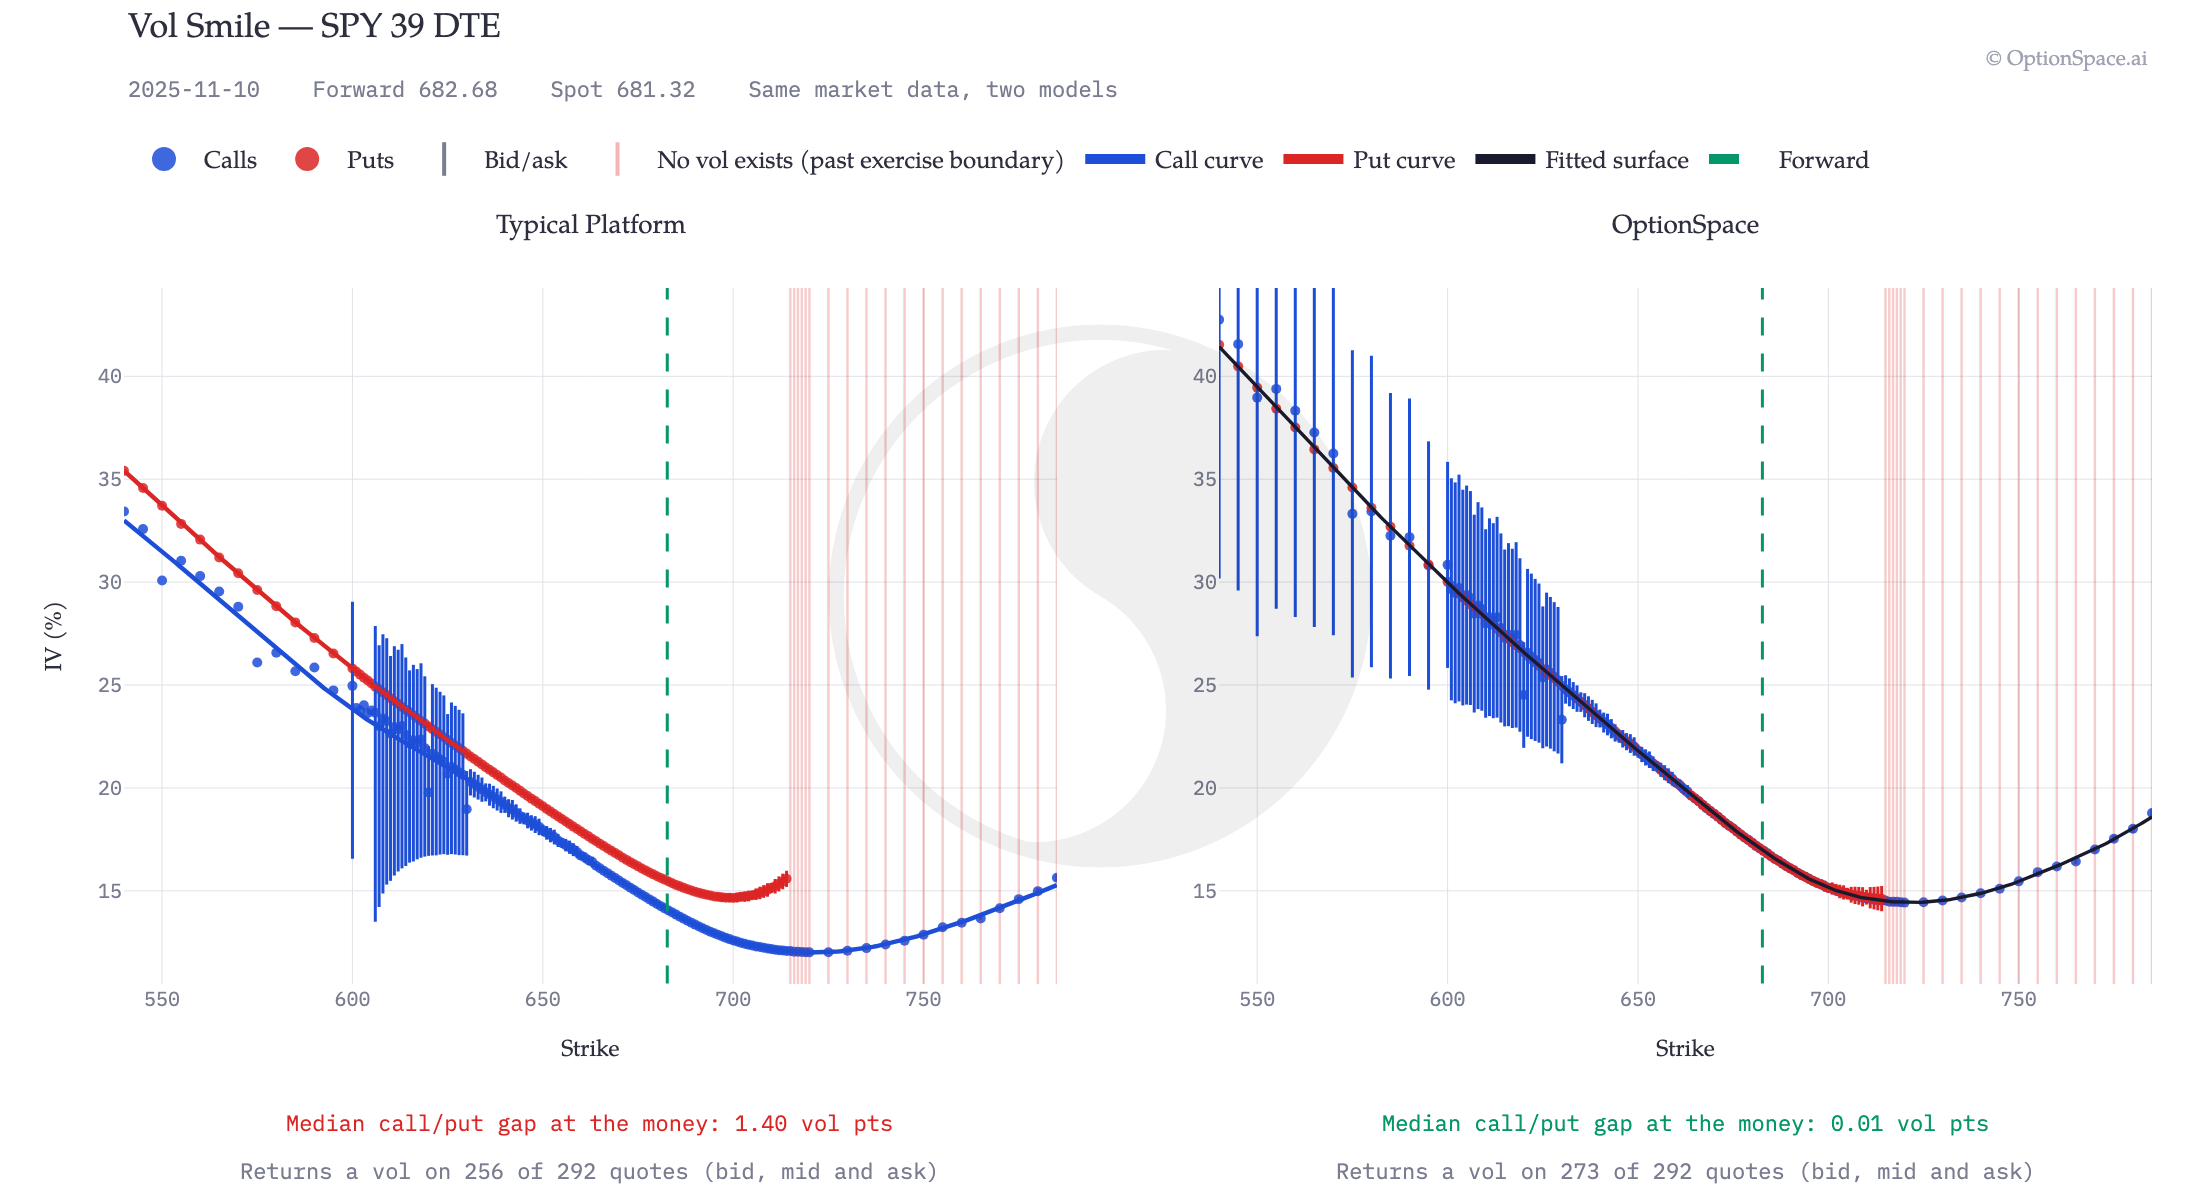
1.40vp At 39 days. Roughly a tick and a half of edge on an at-the-money option.
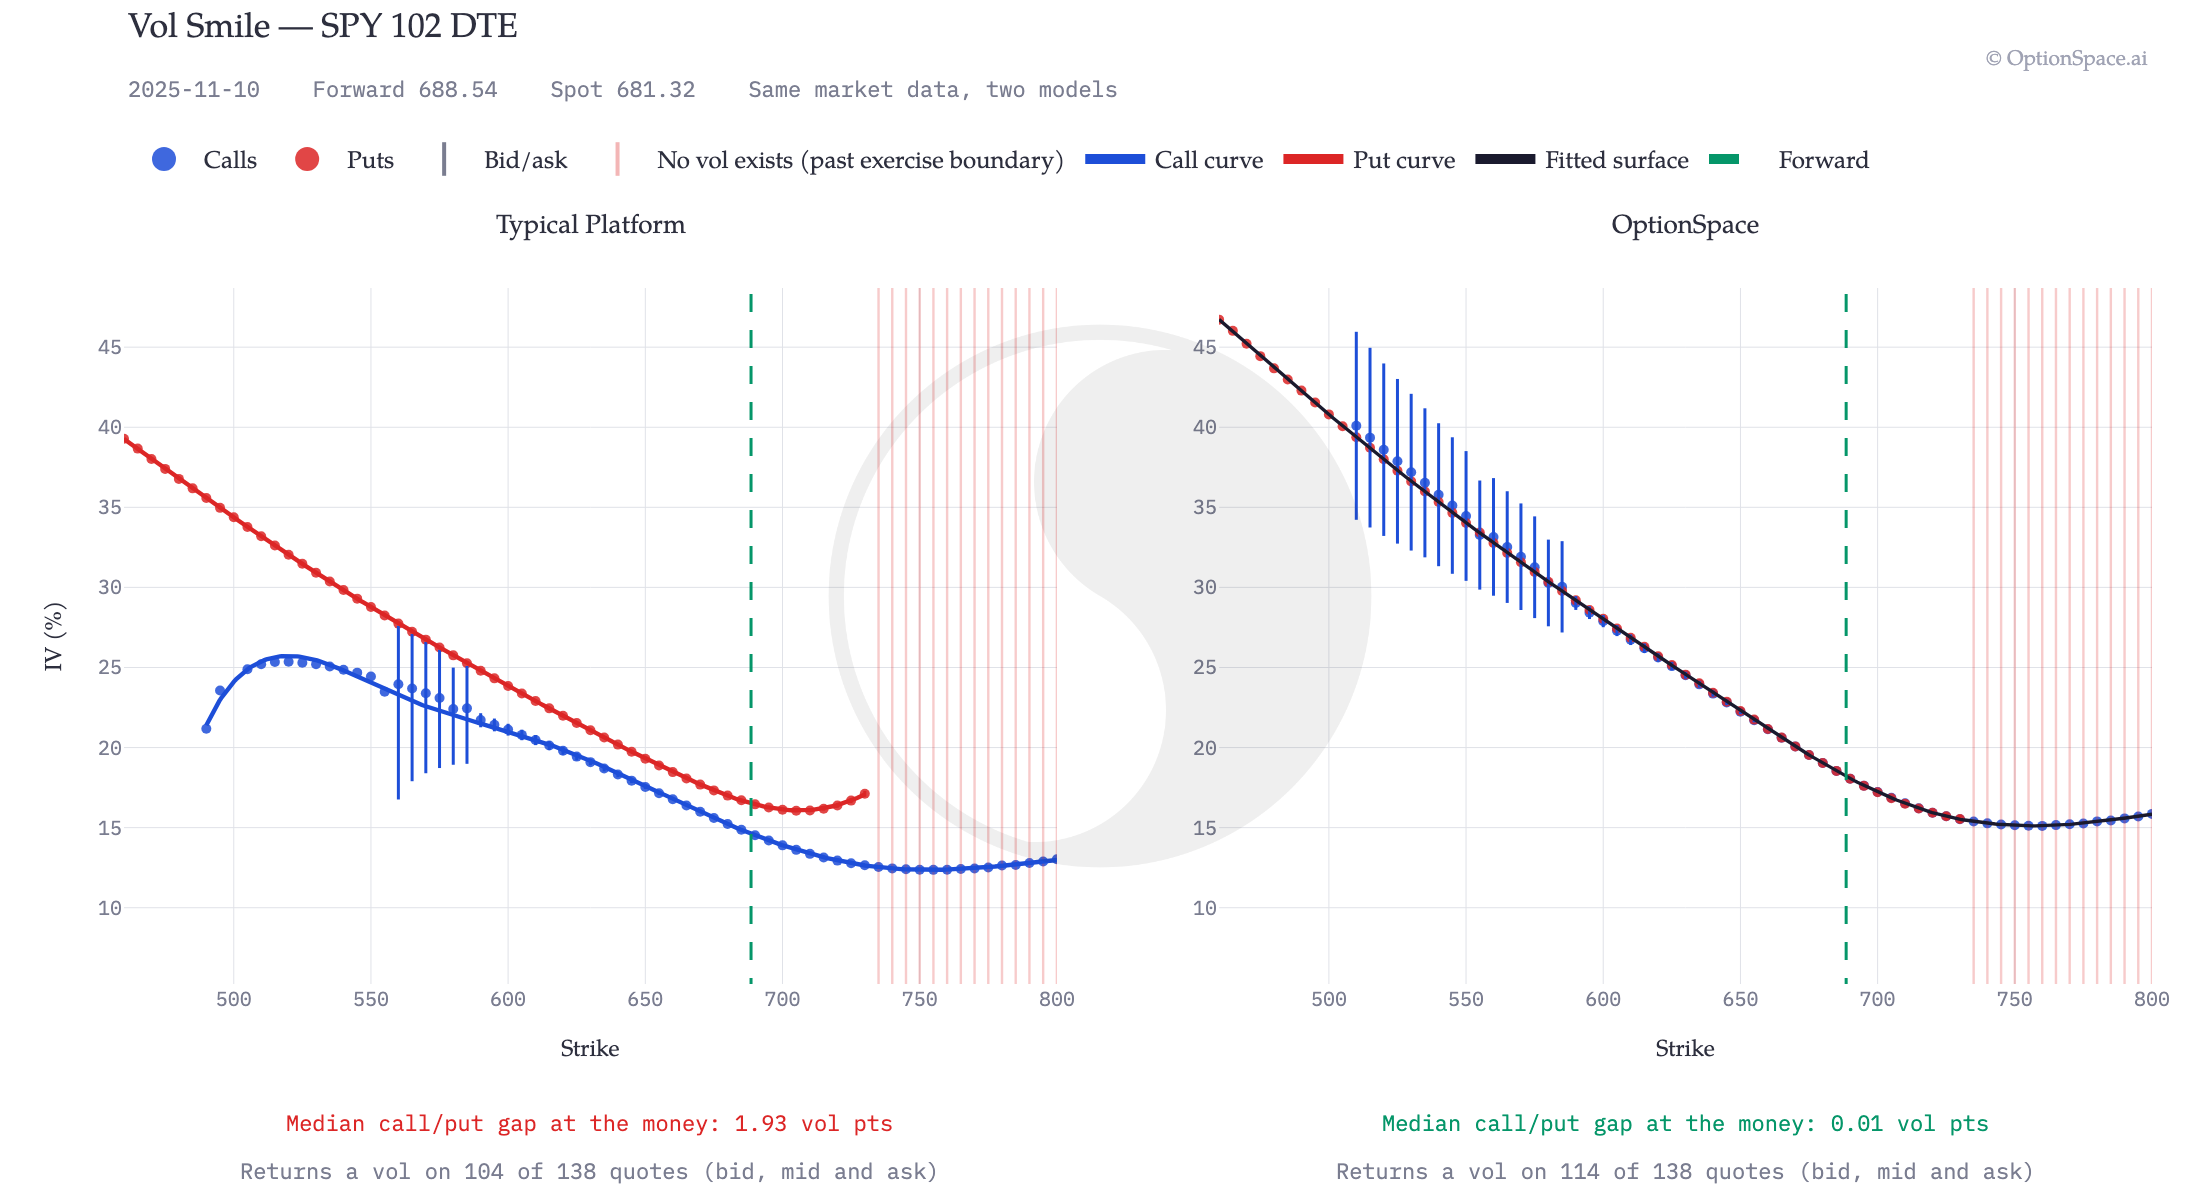
1.93vp At 102 days. The disagreement widens with maturity.
0.01vp Ours, at every one of those tenors.
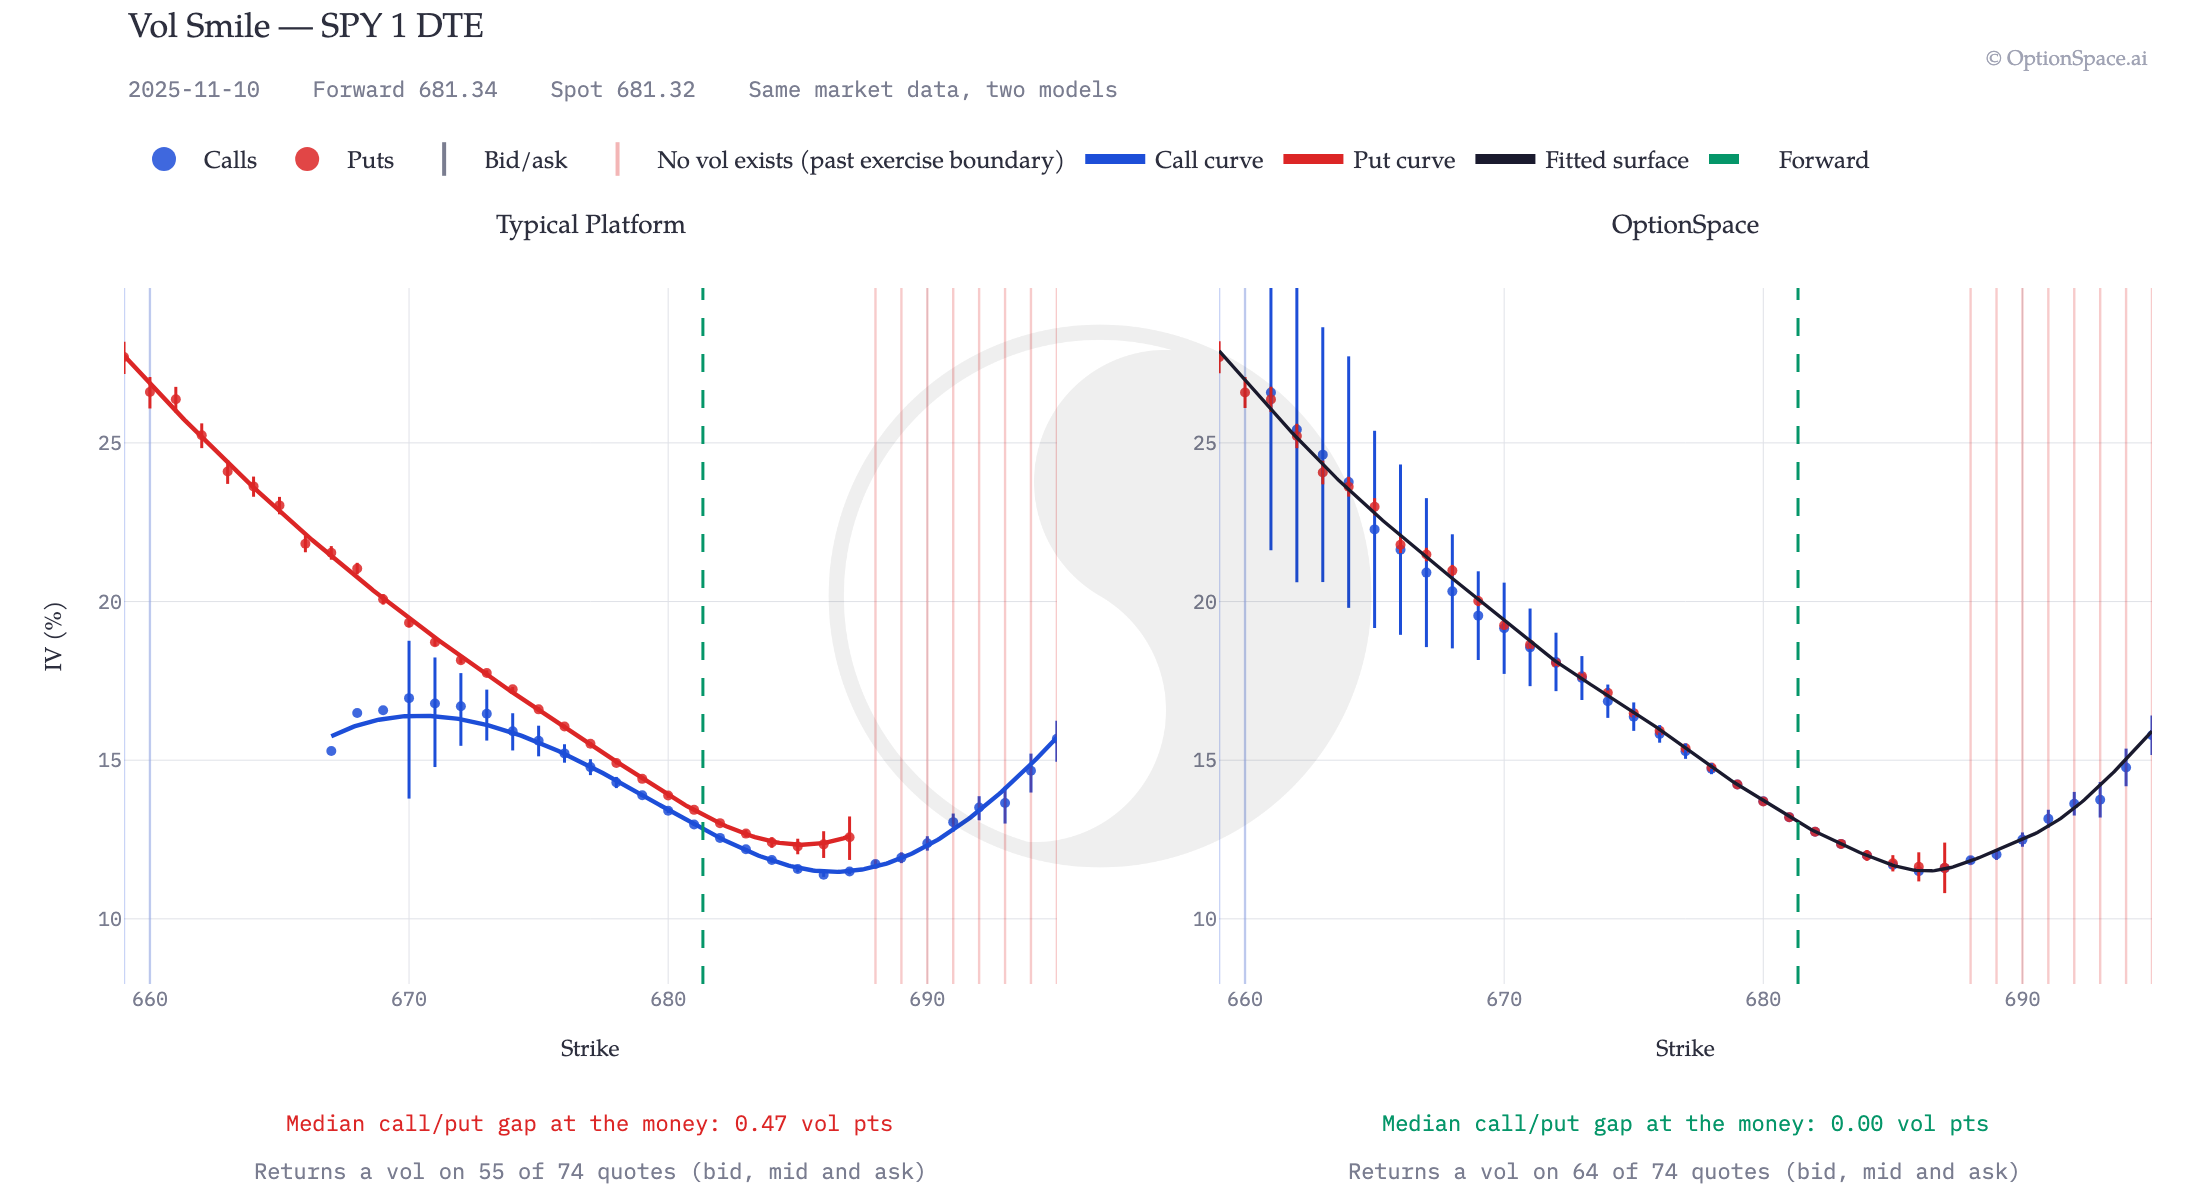
Chart labels reading “Typical Platform” refer to the simplified benchmark defined here; they are not a test of a named provider. The benchmark includes risk-free carry, with zero dividends and borrow.

1 Day to Expiry: The Error Is Already There

Even for a 1 DTE option, using a flat-rate, zero-dividend European benchmark creates a measurable call/put divergence. On the left panel, the naive model produces two separate curves, one for calls and one for puts, that should be a single line.

SPY 1 DTE vol smile, two panels. Left: the simplified European benchmark separates calls from puts by about half a vol point. Right: the OptionSpace fit puts both on one curve. SPY 1 DTE vol smile, two panels. Left: the simplified European benchmark separates calls from puts by about half a vol point. Right: the OptionSpace fit puts both on one curve.
Fig. 01SPY, 1 day to expiry, 10 November 2025. Same quotes on both sides.

Left: 0.47 vol point gap. The call curve (blue) and put curve (red) diverge because the model can't produce a single consistent surface.
Right: 0.00 vol point gap. Calls and puts overlap within their bid/ask spread. One clean curve fits both.

39 DTE: Dividends Break Naive Pricing

SPY pays a ~$2 dividend every quarter. December 19 is the Q4 ex-dividend date, and this expiry lands right after it. A model using spot + SOFR doesn't know about dividends at all. The $2 dividend translates directly into a forward pricing error.

SPY 39 DTE vol smile, two panels. Left: the simplified European benchmark splits calls and puts into two curves 1.4 vol points apart. Right: the OptionSpace fit puts both on one curve. SPY 39 DTE vol smile, two panels. Left: the simplified European benchmark splits calls and puts into two curves 1.4 vol points apart. Right: the OptionSpace fit puts both on one curve.
Fig. 02SPY, 39 days to expiry, 10 November 2025. The median at‑the‑money disagreement between the call and the put is 1.40 vol points on the left and 0.01 on the right, on identical quotes.

Left: 1.40 vol point gap from ignoring the $2 dividend. Growing spot at a flat 4.58% gives a forward of 684.83 where the market's own forward is 682.68; $2.15 too high, which is the dividend. Too high a forward makes calls look further in the money than they are, so it takes less vol to reproduce their price and more to reproduce the puts': the call curve sits below the put curve at every strike. Every greek derived from either curve is wrong.
Right: 0.01 vol point gap. Our model implies the forward from the market, automatically capturing the dividend's effect. One curve fits both.

102 DTE: The Error Compounds

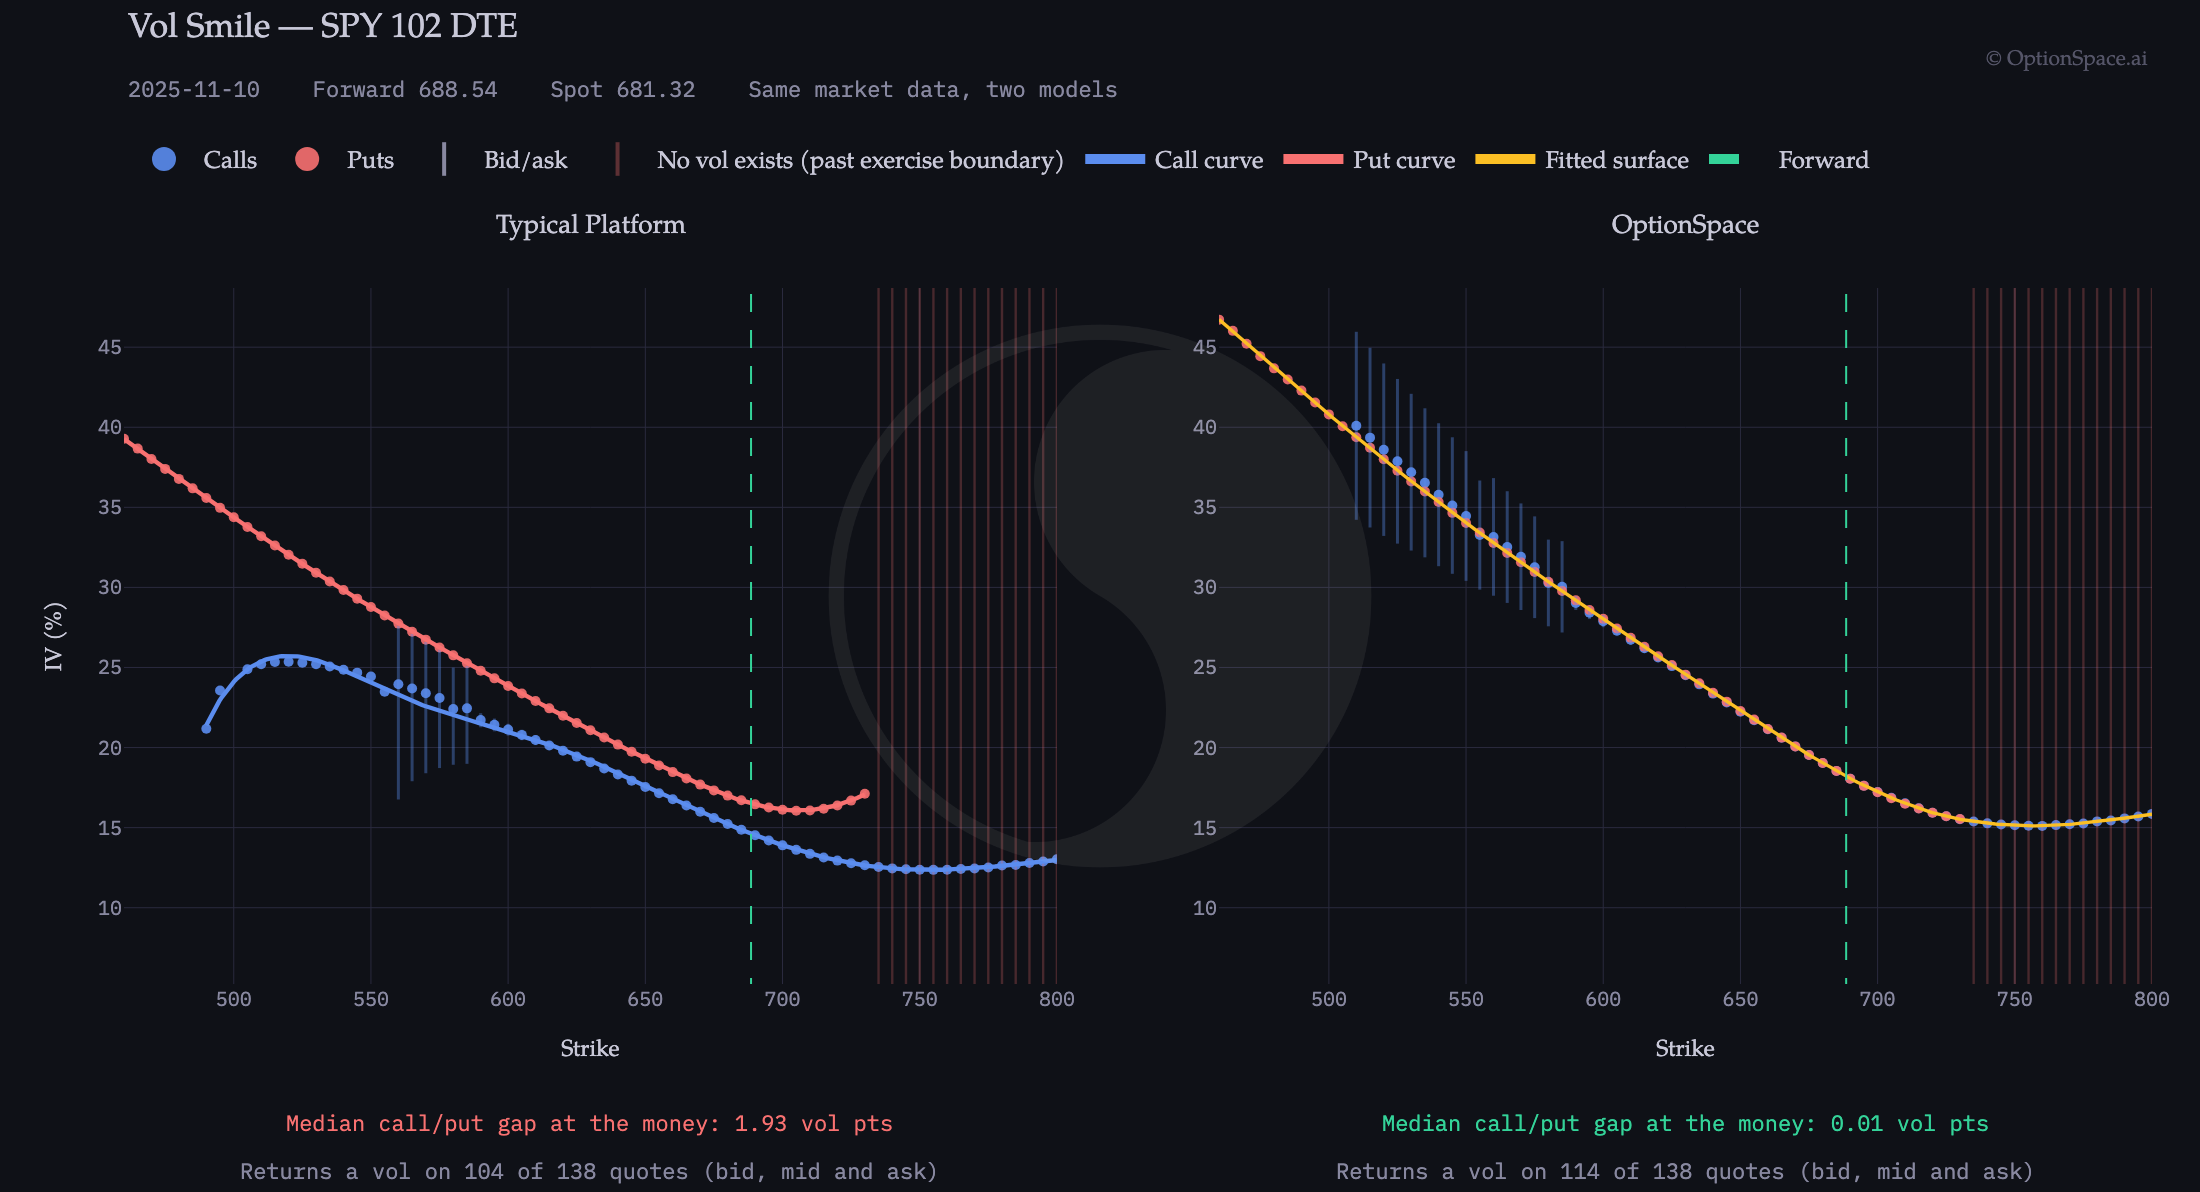
At 102 days to expiry, the naive model has accumulated multiple dividend misses and rate curve errors. The call/put divergence is nearly 2 vol points.

SPY 102 DTE vol smile, two panels. Left: calls and puts sit on two curves 1.93 vol points apart. Right: one curve fits both. SPY 102 DTE vol smile, two panels. Left: calls and puts sit on two curves 1.93 vol points apart. Right: one curve fits both.
Fig. 03SPY, 102 days to expiry. 1.93 vol points apart on the left, 0.01 on the right.

What this means for you: If you're backtesting a strategy on 3-month options, every entry and exit price in your backtest is wrong by the amount this curve is off. If you're hedging with deltas from this surface, your hedge ratios are systematically biased. The error isn't random. It's a consistent directional bias: at 102 days the naive call vol lands below the naive put vol at all 11 at-the-money strikes, not most of them.

It's Not Just SPY

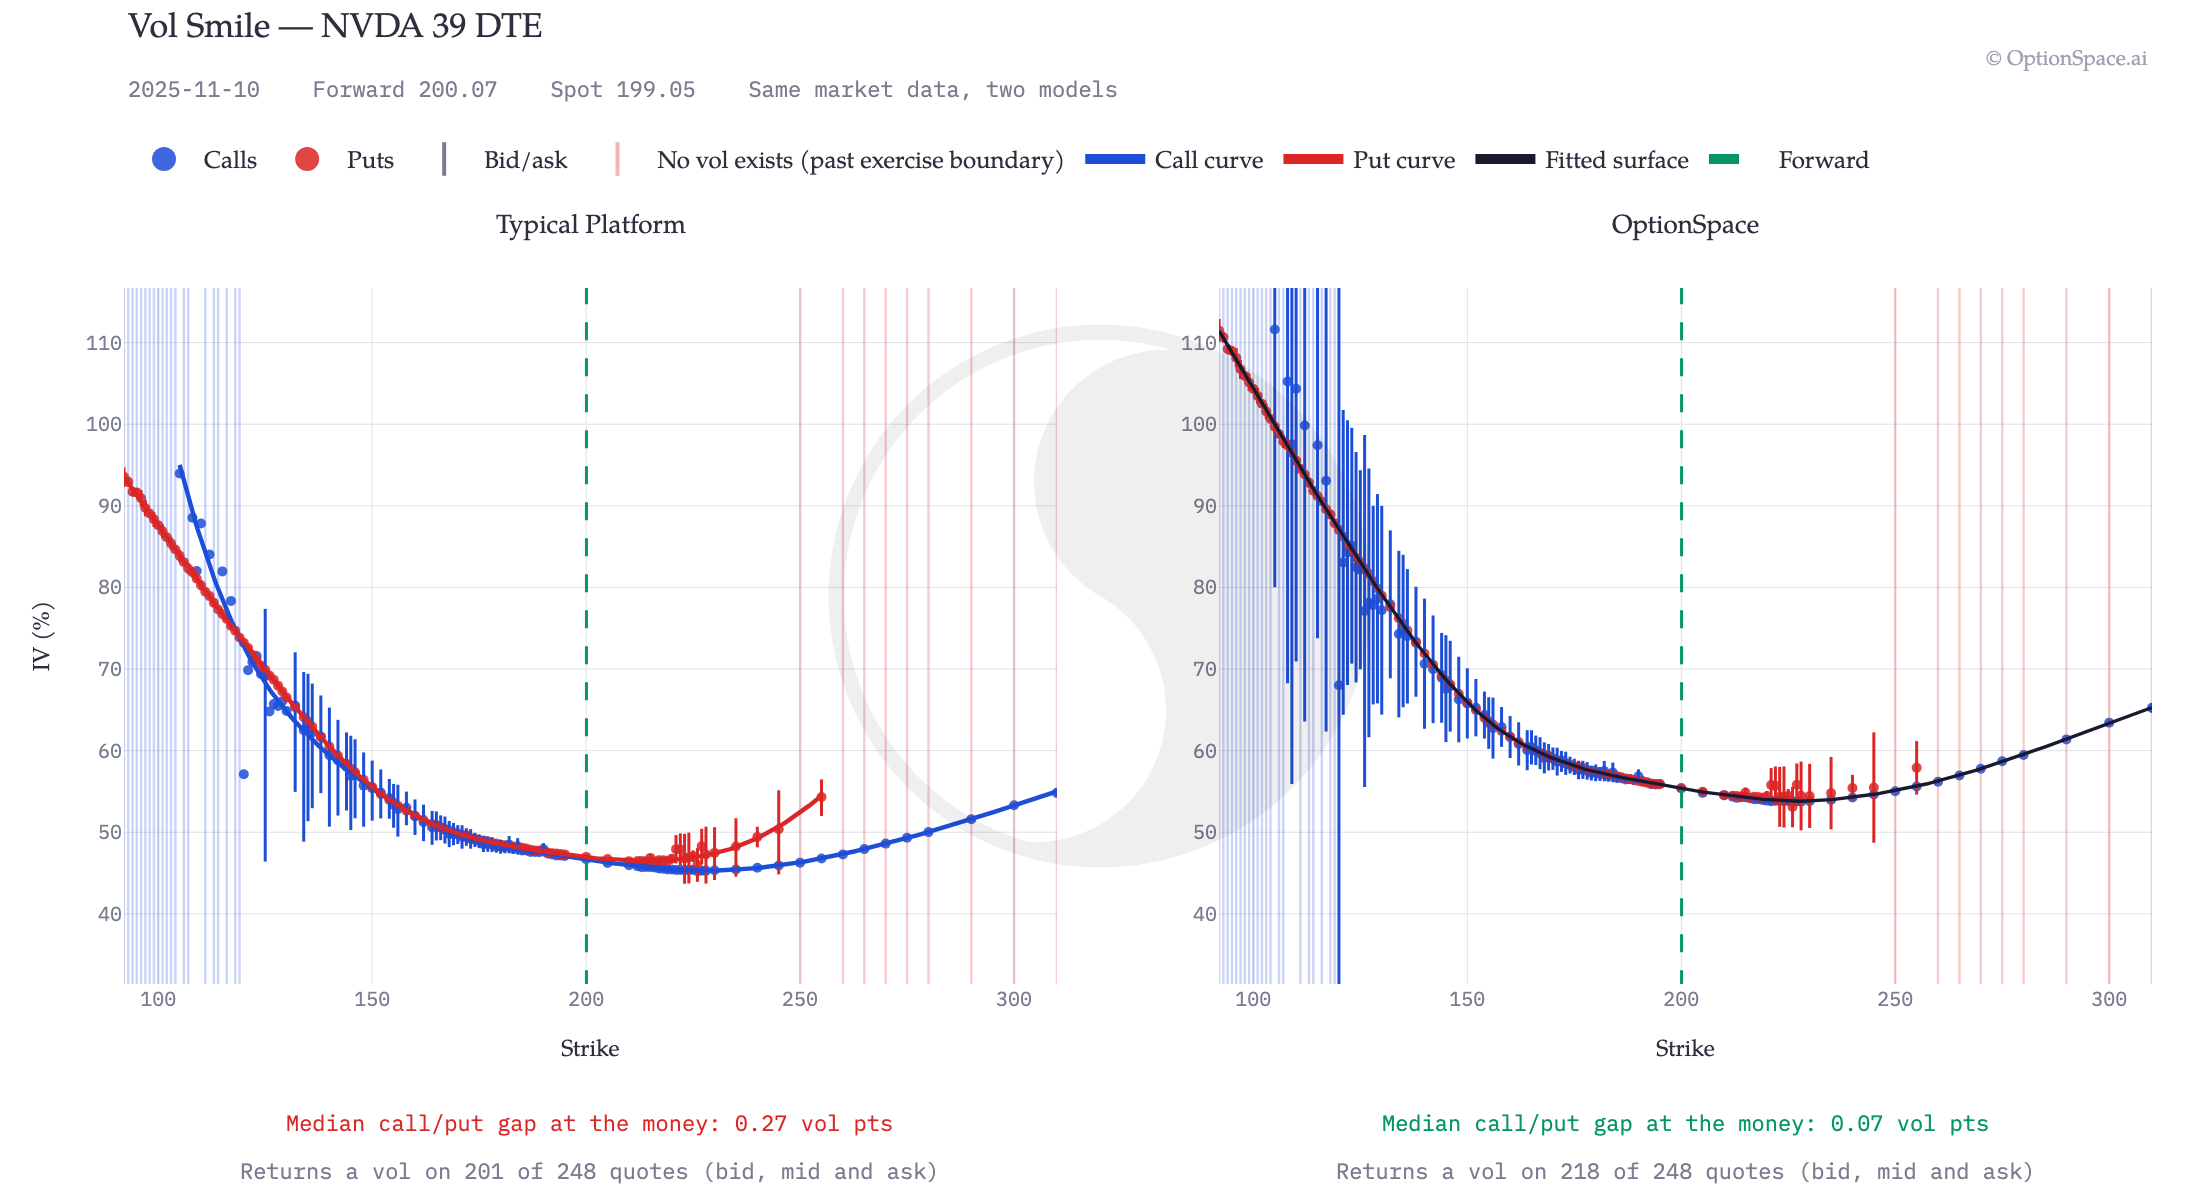
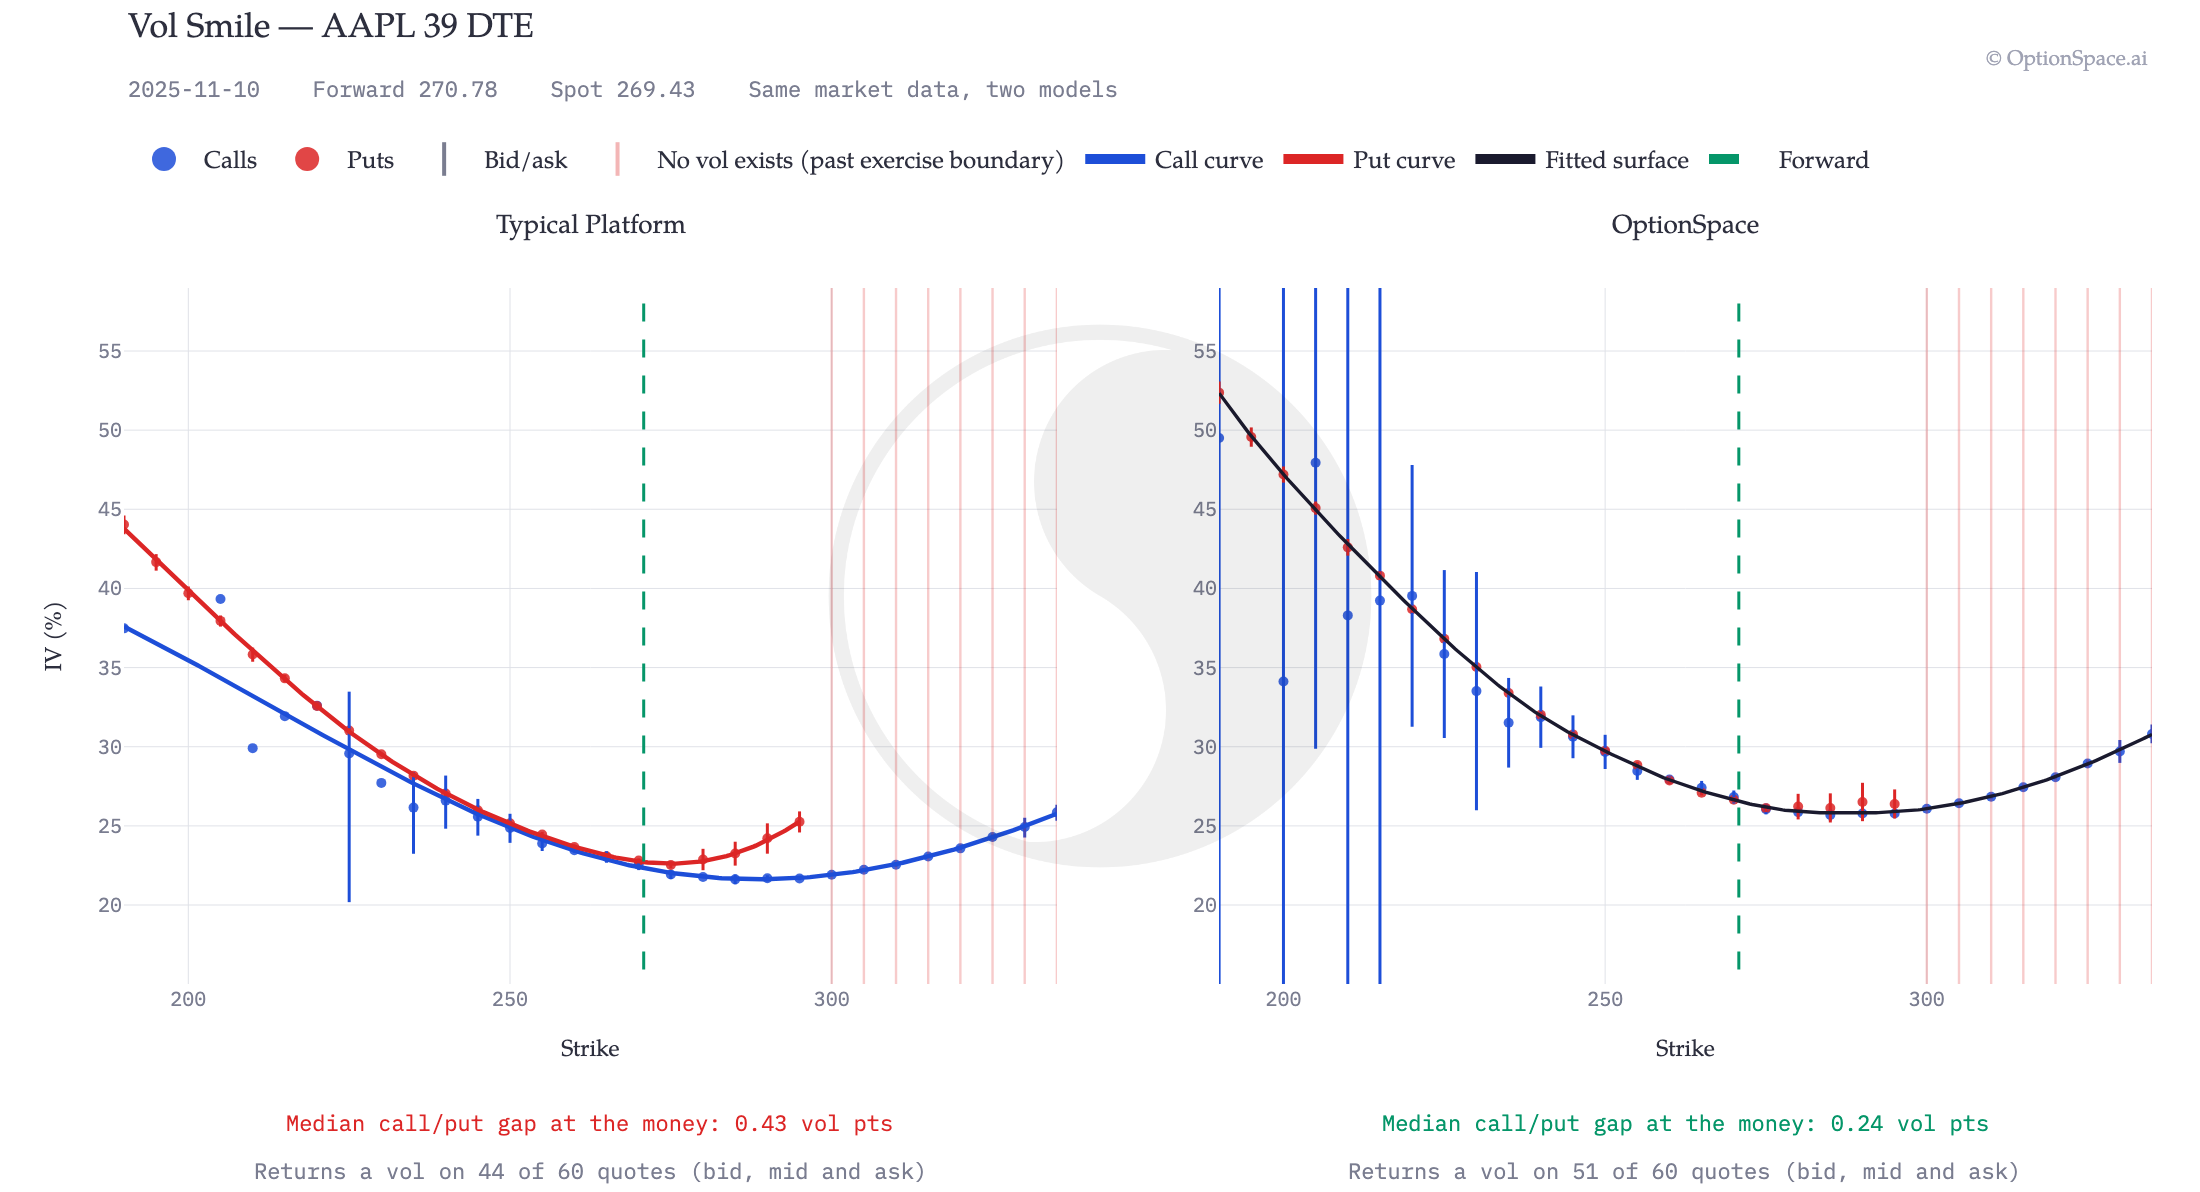
Every American-exercise option has this problem. Here's the same comparison for NVDA and AAPL. Even without a meaningful dividend on this specific expiry, the benchmark's use of assumed carry instead of an implied forward creates a persistent call/put gap.

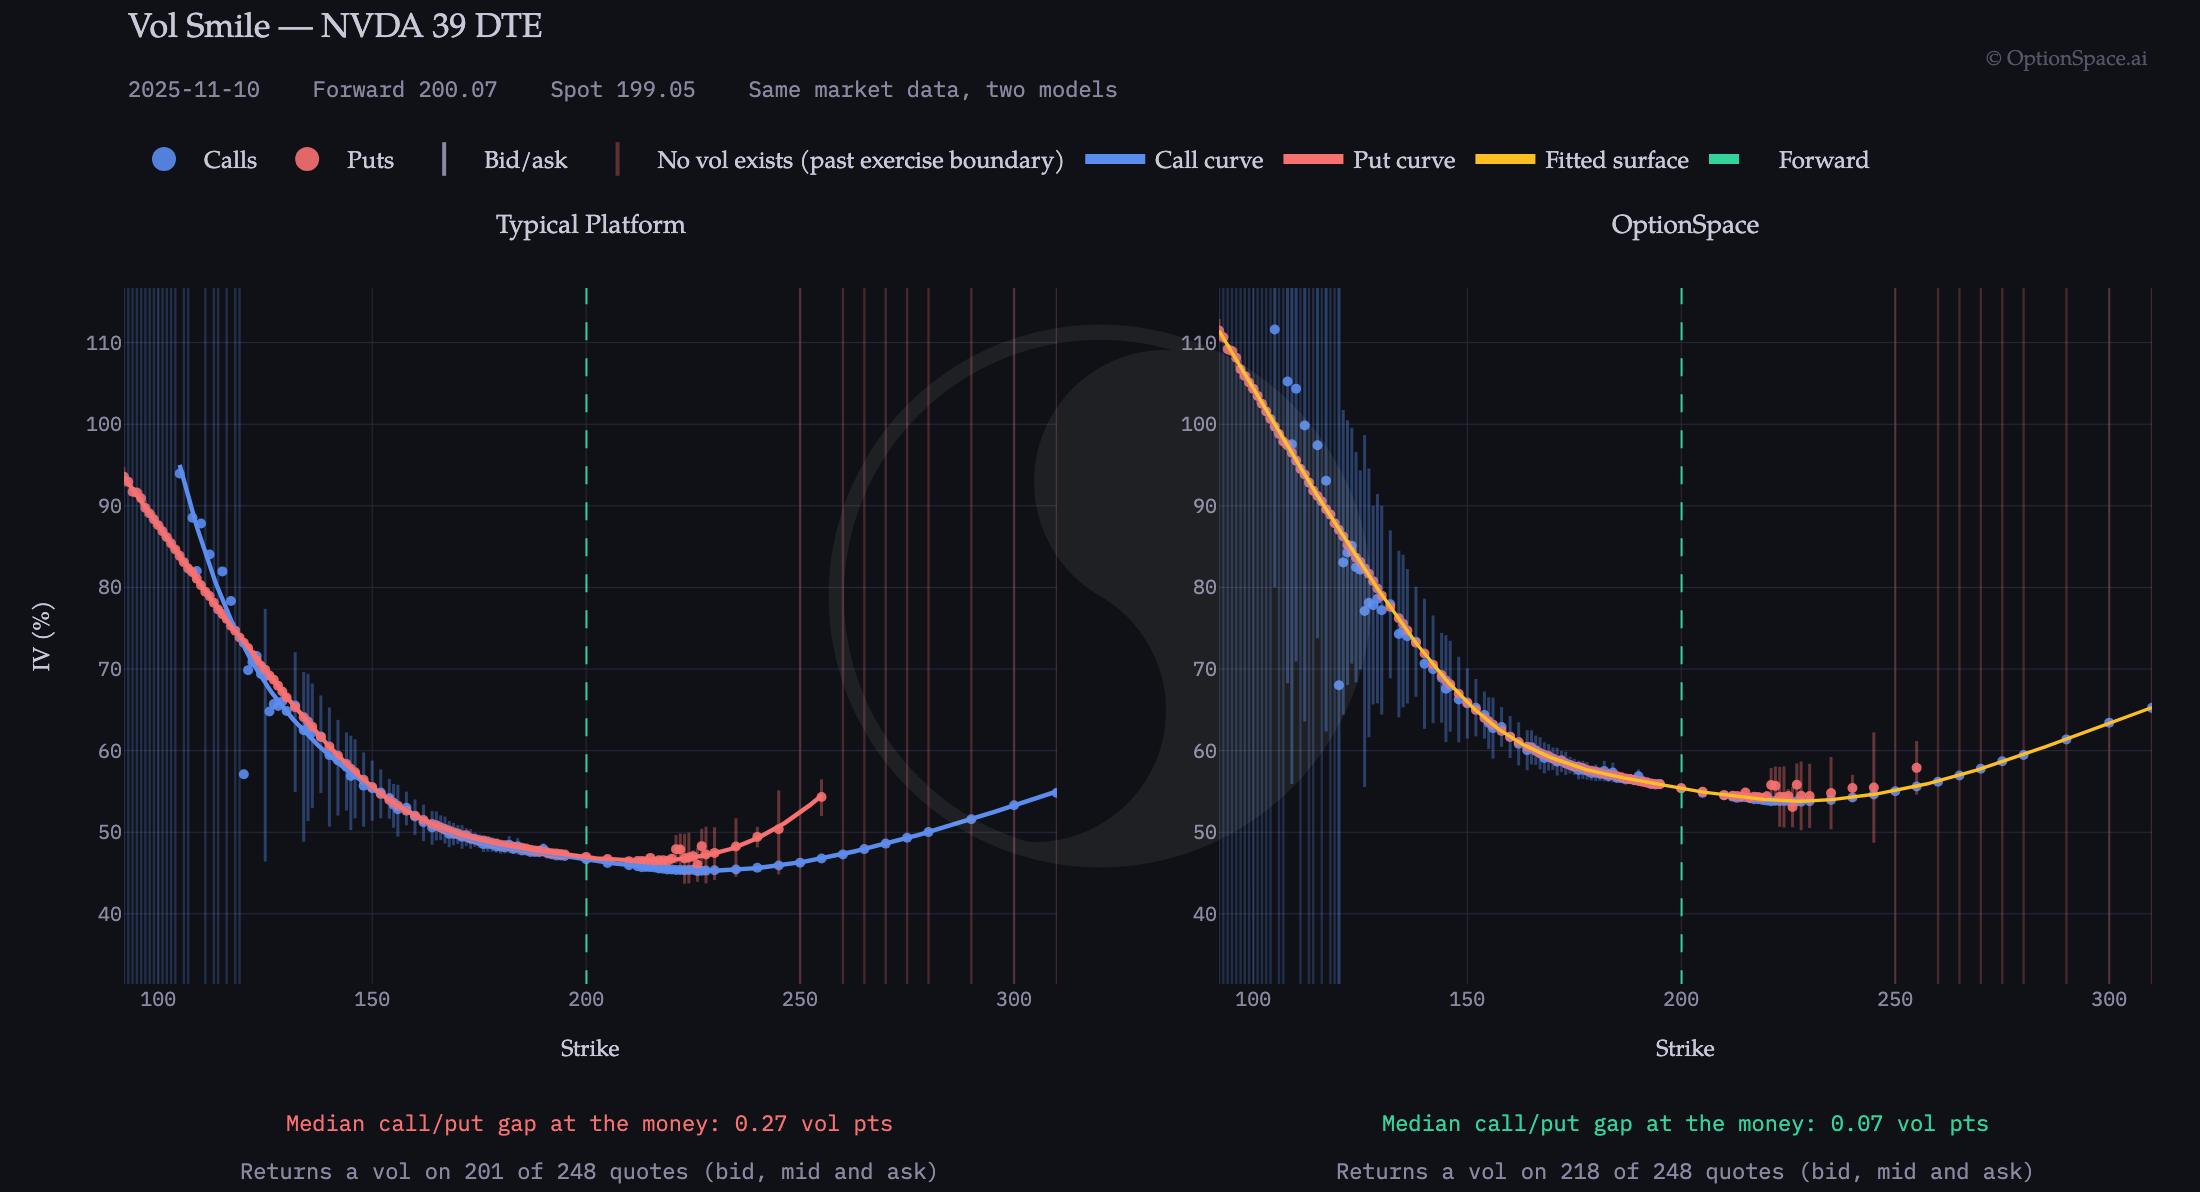
NVDA 39 DTE vol smile, two panels. The naive panel's call and put curves are 0.27 vol points apart; the OptionSpace panel's are 0.07 apart. NVDA 39 DTE vol smile, two panels. The naive panel's call and put curves are 0.27 vol points apart; the OptionSpace panel's are 0.07 apart.
Fig. 04NVDA, 39 days to expiry, same afternoon.

NVDA: Naive gap of 0.27 vol pts vs our 0.07. The gap comes from the wrong forward and ignoring borrow costs: it grows for longer-dated options.

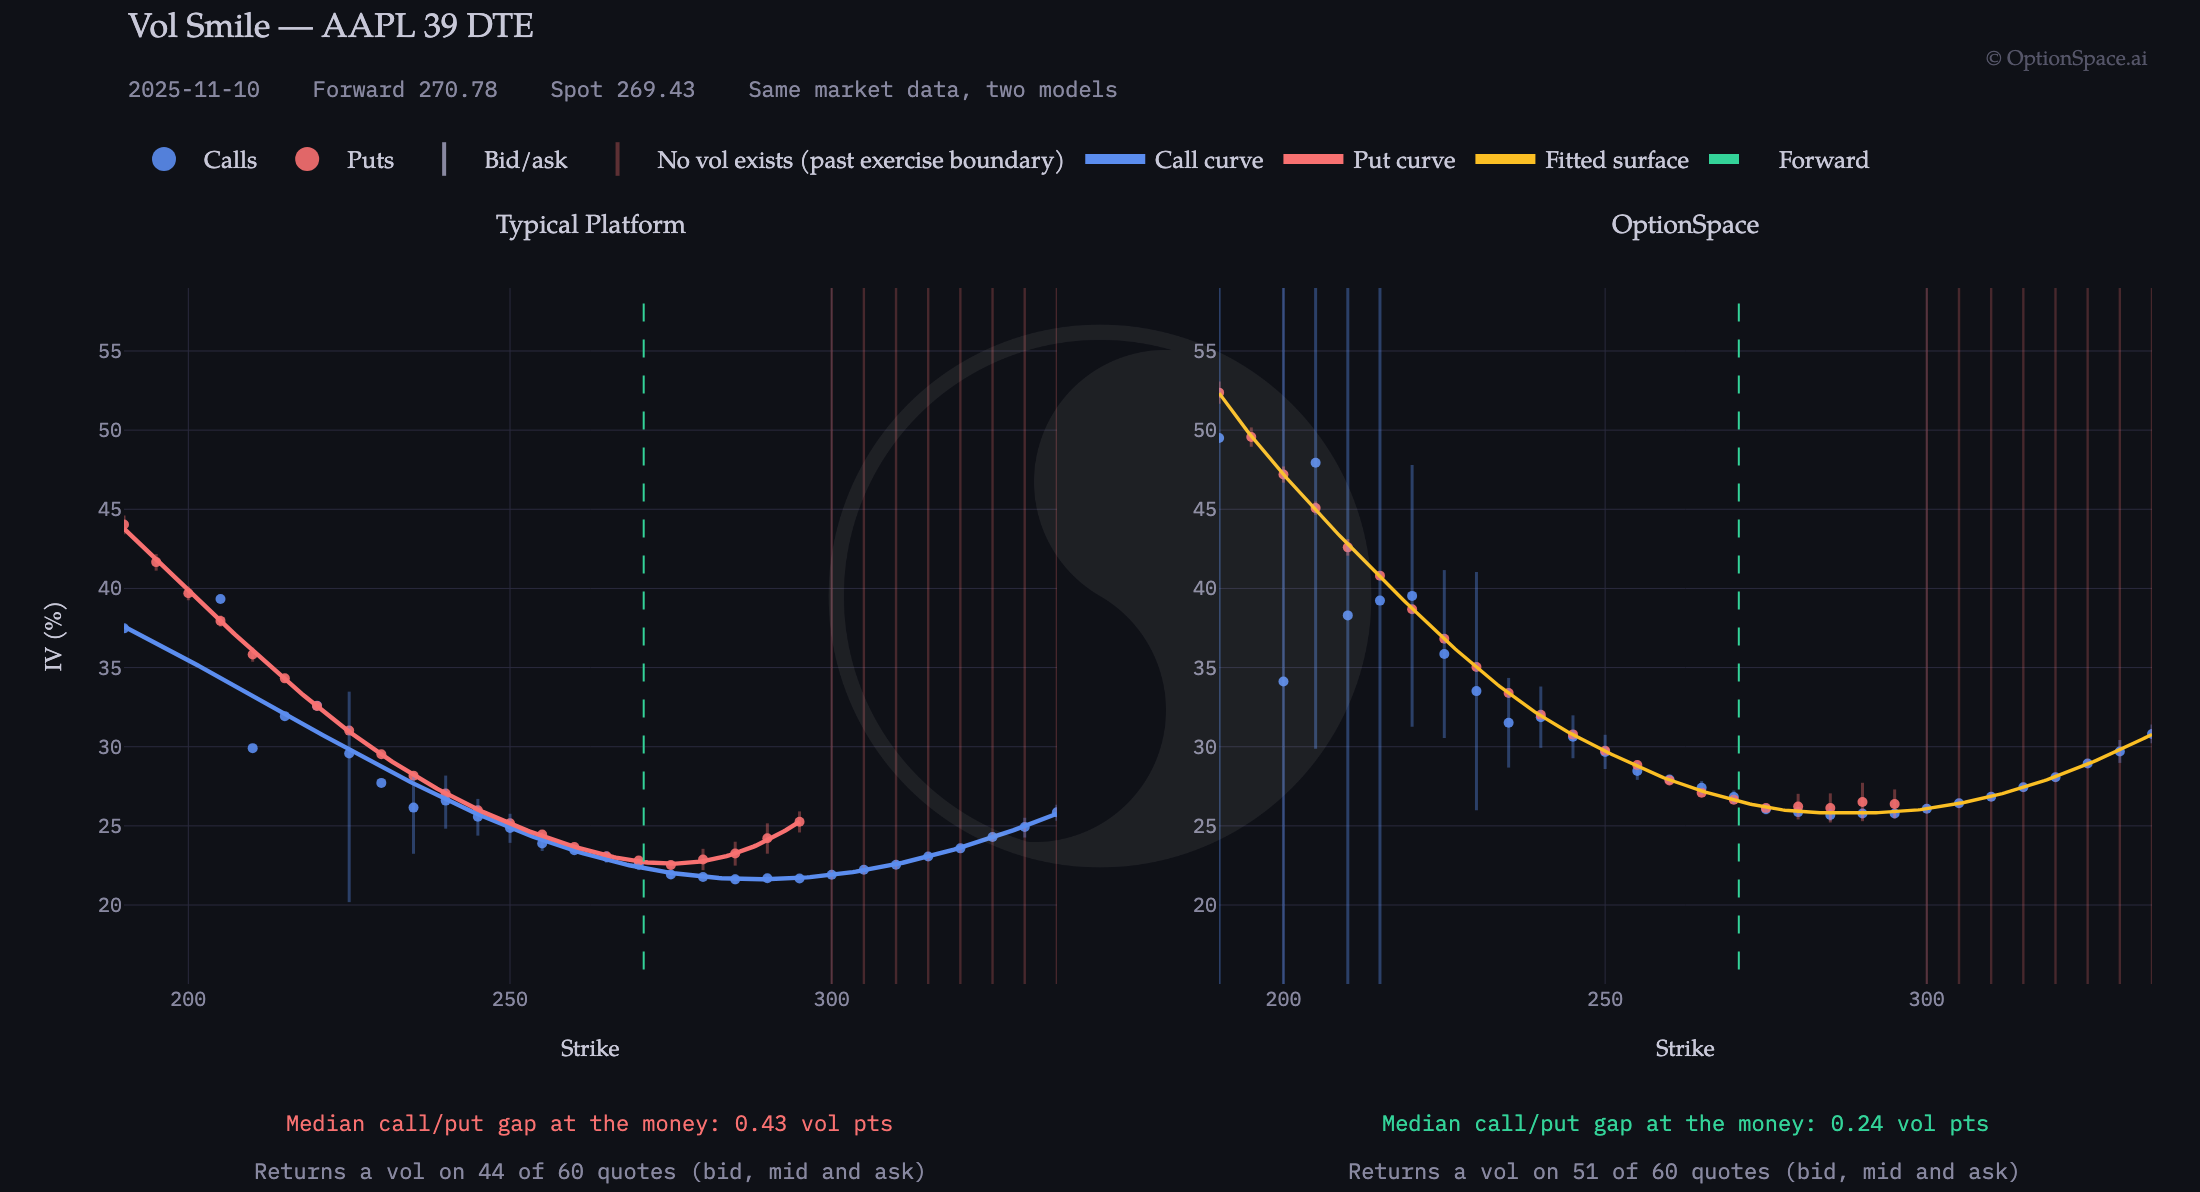
AAPL 39 DTE vol smile, two panels. The naive panel's call and put curves are 0.43 vol points apart; the OptionSpace panel's are 0.24 apart. AAPL 39 DTE vol smile, two panels. The naive panel's call and put curves are 0.43 vol points apart; the OptionSpace panel's are 0.24 apart.
Fig. 05AAPL, 39 days to expiry, same afternoon.

AAPL: Naive gap of 0.43 vol pts vs our 0.24. AAPL's quarterly dividend is small (~$0.25), but combined with early exercise and borrow costs, the naive model's divergence propagates to every greek.

The Problem Grows With Maturity

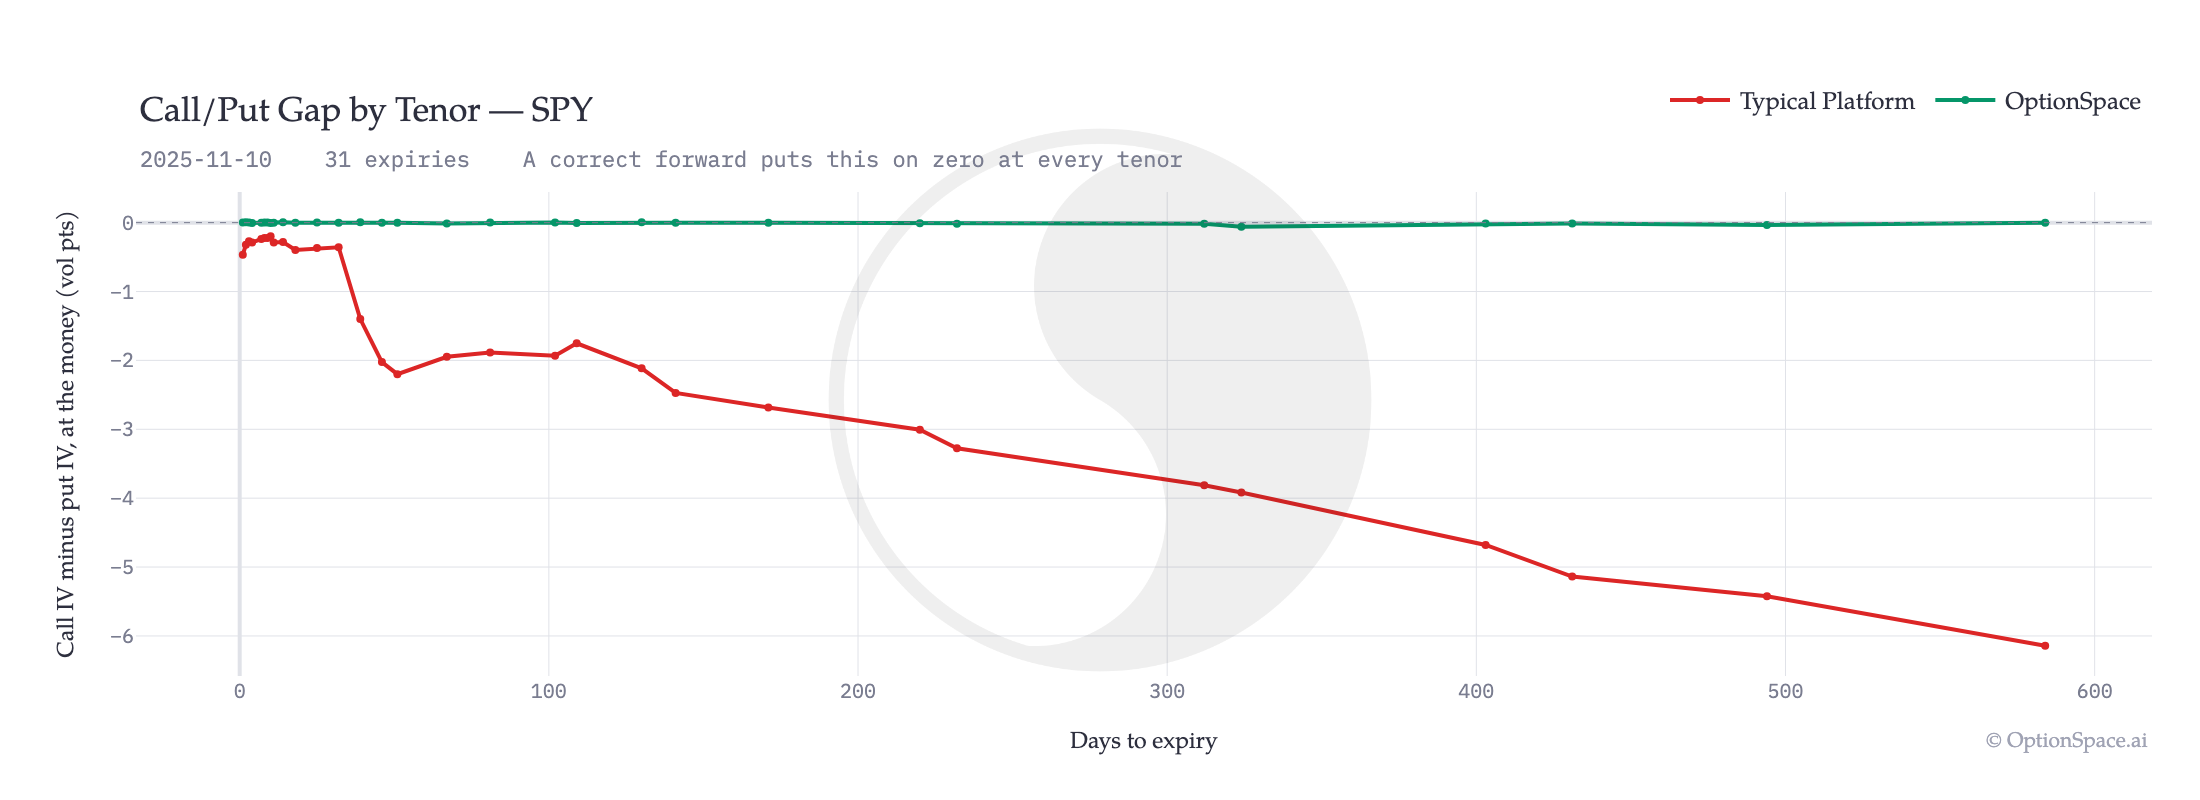
Here's the ATM call/put IV gap across every available expiry, from 1 day to over 1 year out. The red line (simplified benchmark) grows steadily as more dividends fall within the option's life. The green line (OptionSpace) stays flat near zero.

Call minus put IV at the money across 31 SPY expiries. The flat-rate, zero-dividend benchmark line runs from zero to about minus six vol points at 584 days; the OptionSpace line stays flat at zero. Call minus put IV at the money across 31 SPY expiries. The flat-rate, zero-dividend benchmark line runs from zero to about minus six vol points at 584 days; the OptionSpace line stays flat at zero.
Fig. 06Every SPY expiry on the board out to 584 days, same afternoon. Two models, one set of quotes. A correct forward puts this line on zero at every tenor.

The red line should be at zero. Every point away from zero represents model error that contaminates the vol surface, the greeks, and every price derived from them. At 584 DTE the naive model produces over 6 vol points of ATM call/put divergence. Ours never leaves 0.06.

Your Greeks Are Wrong Too

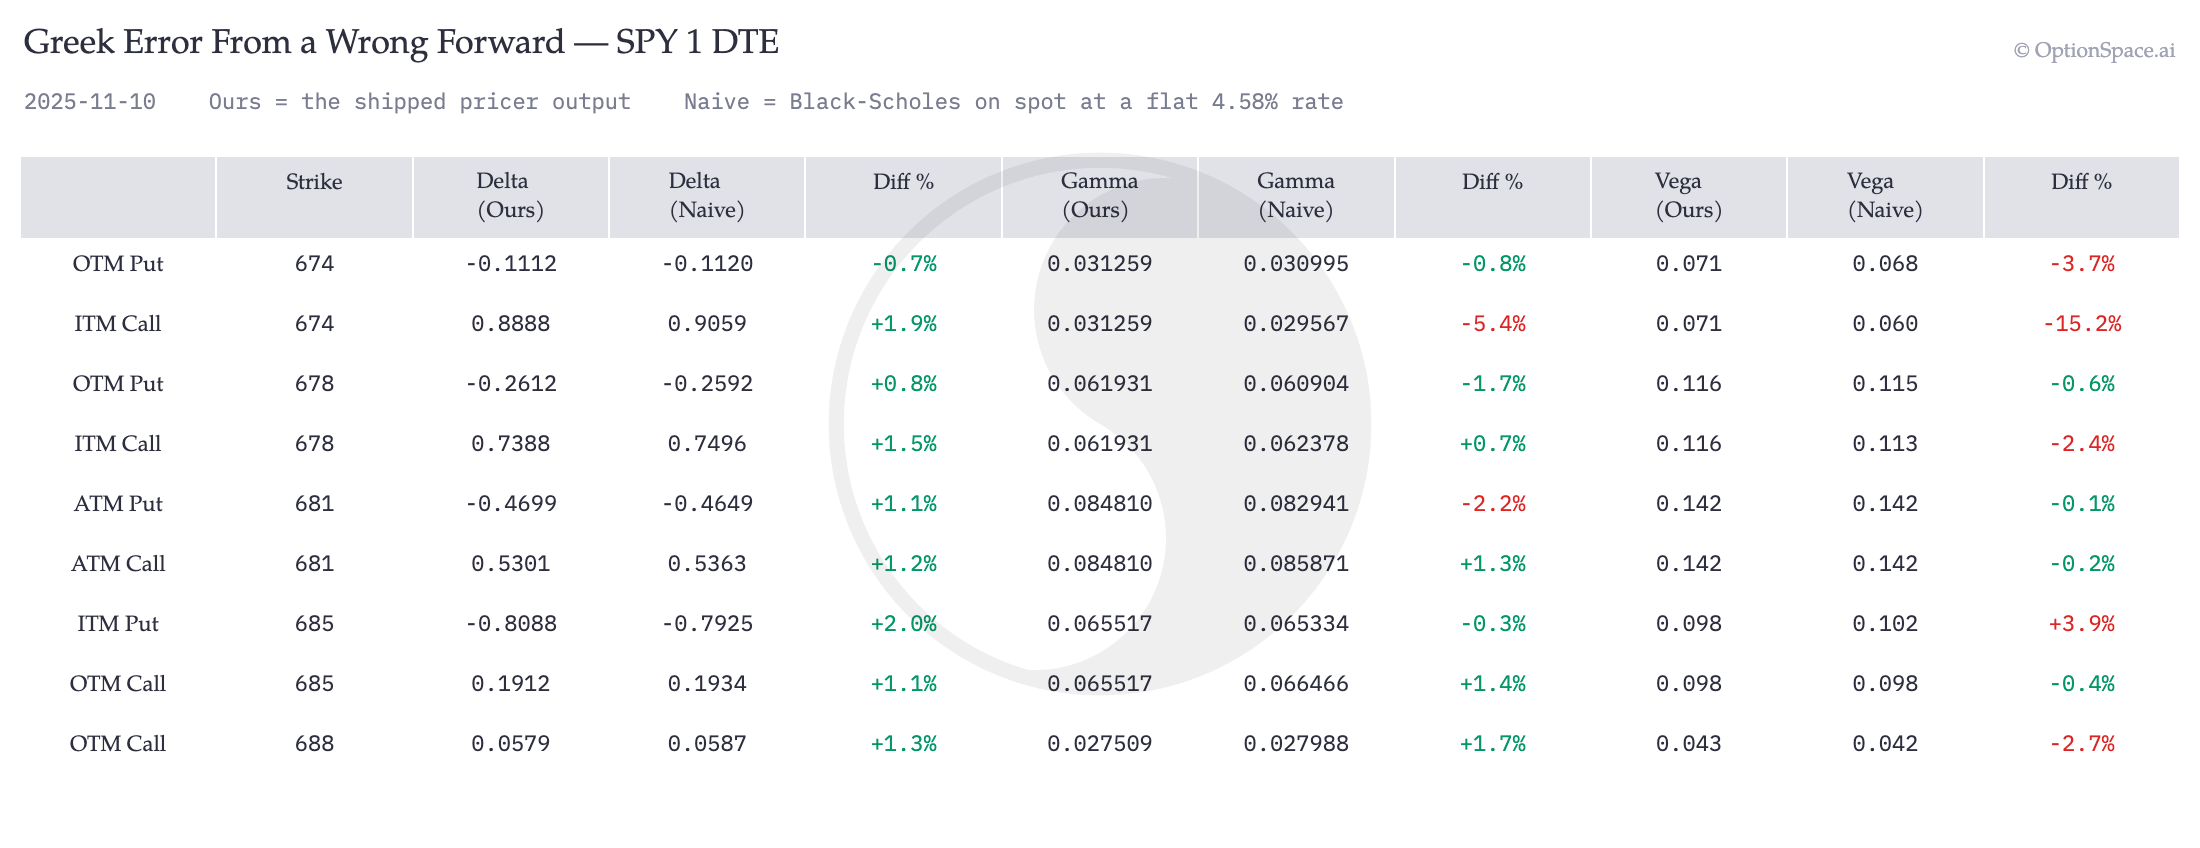
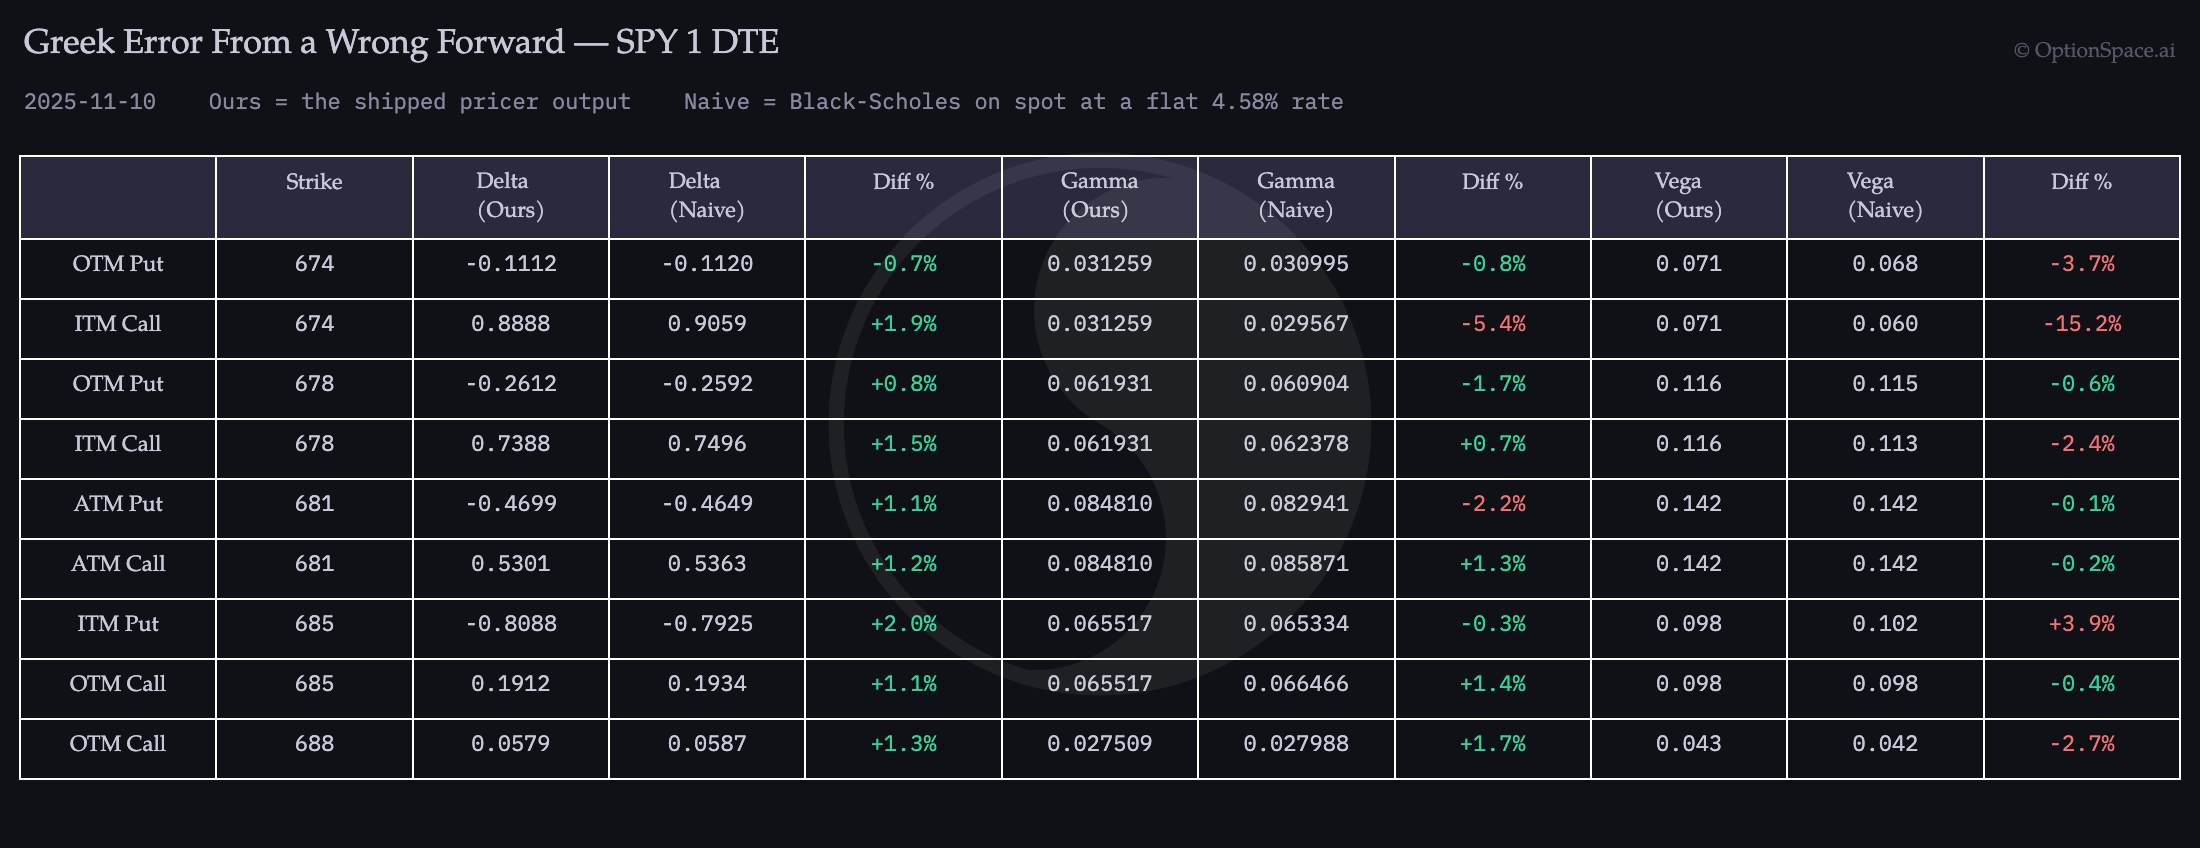
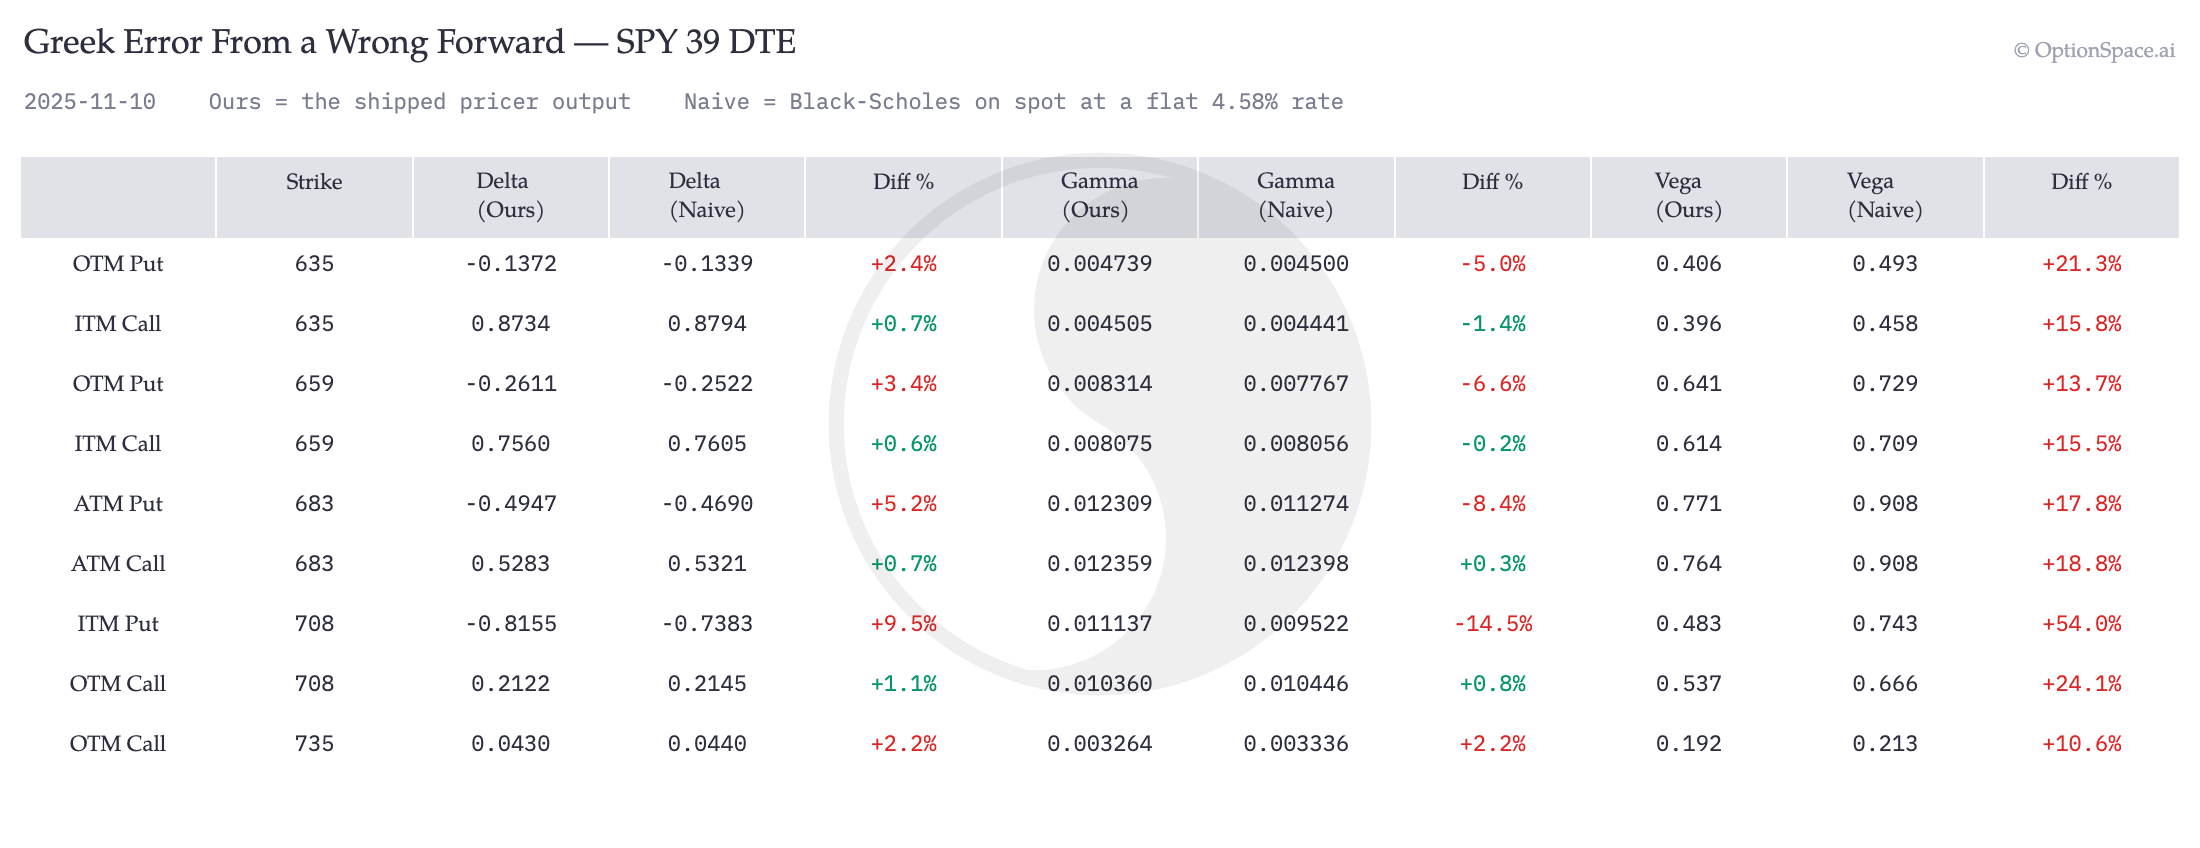
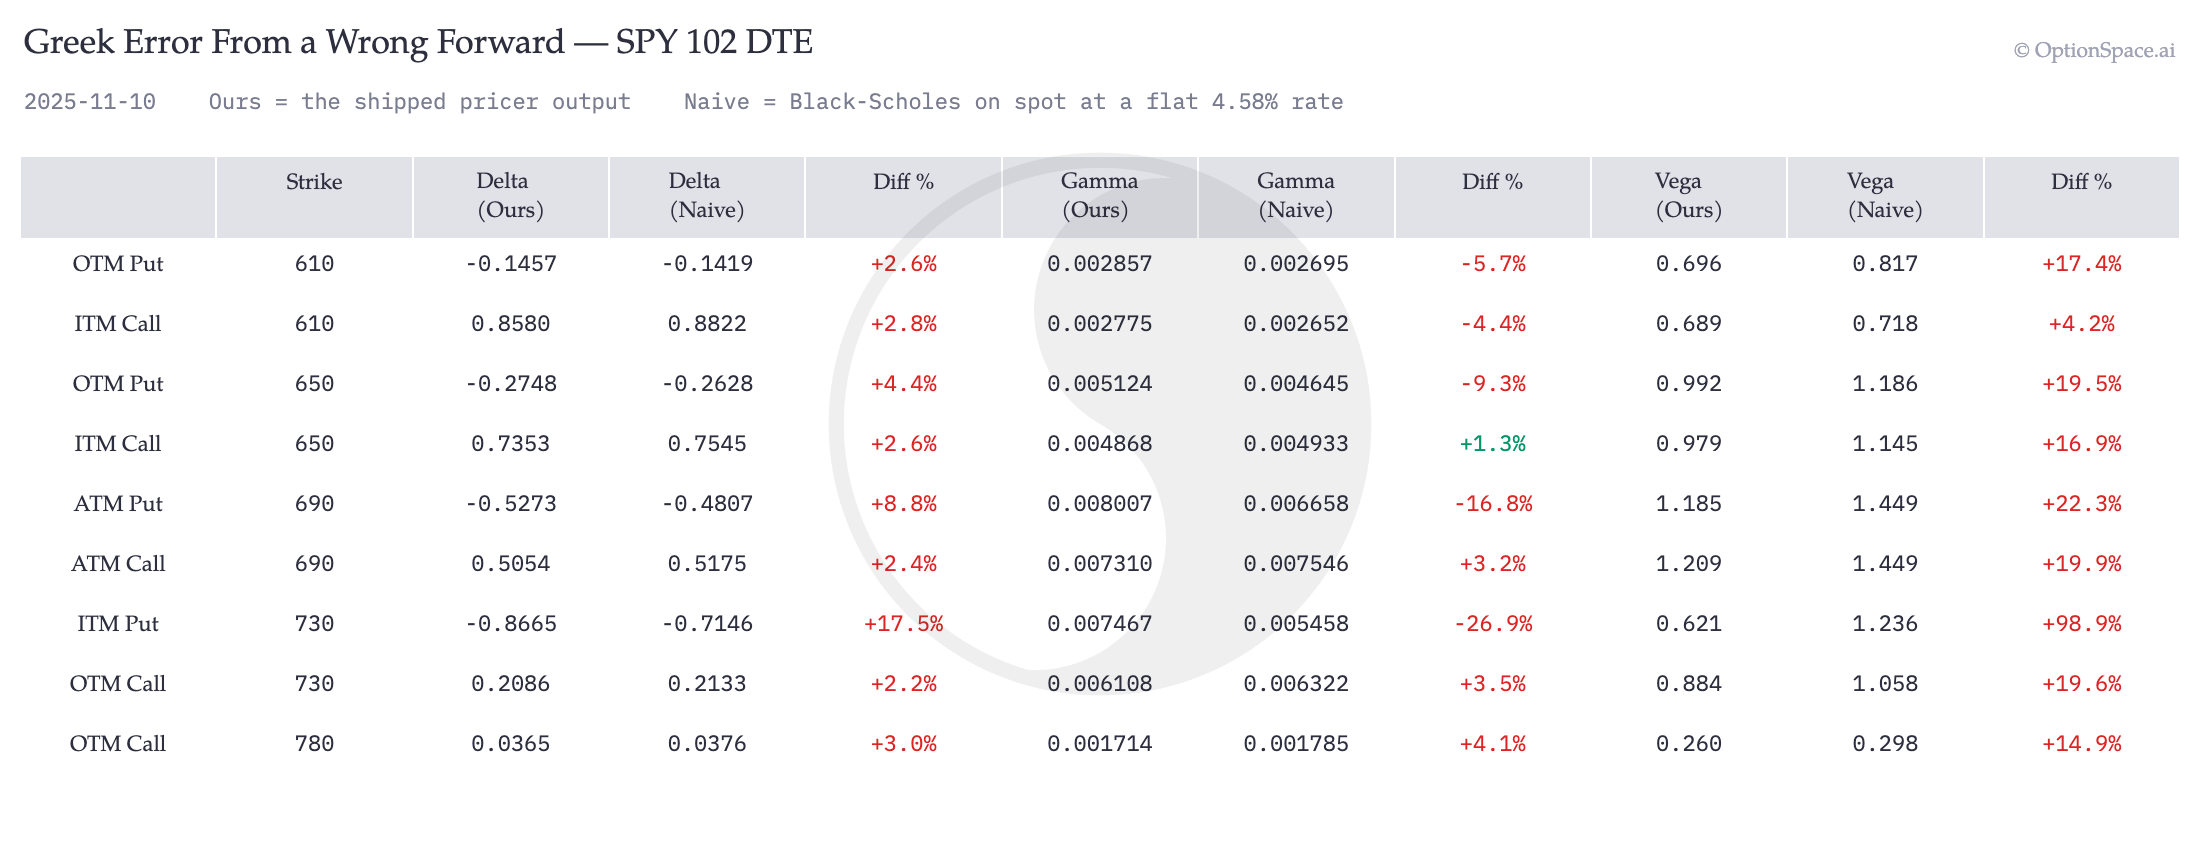
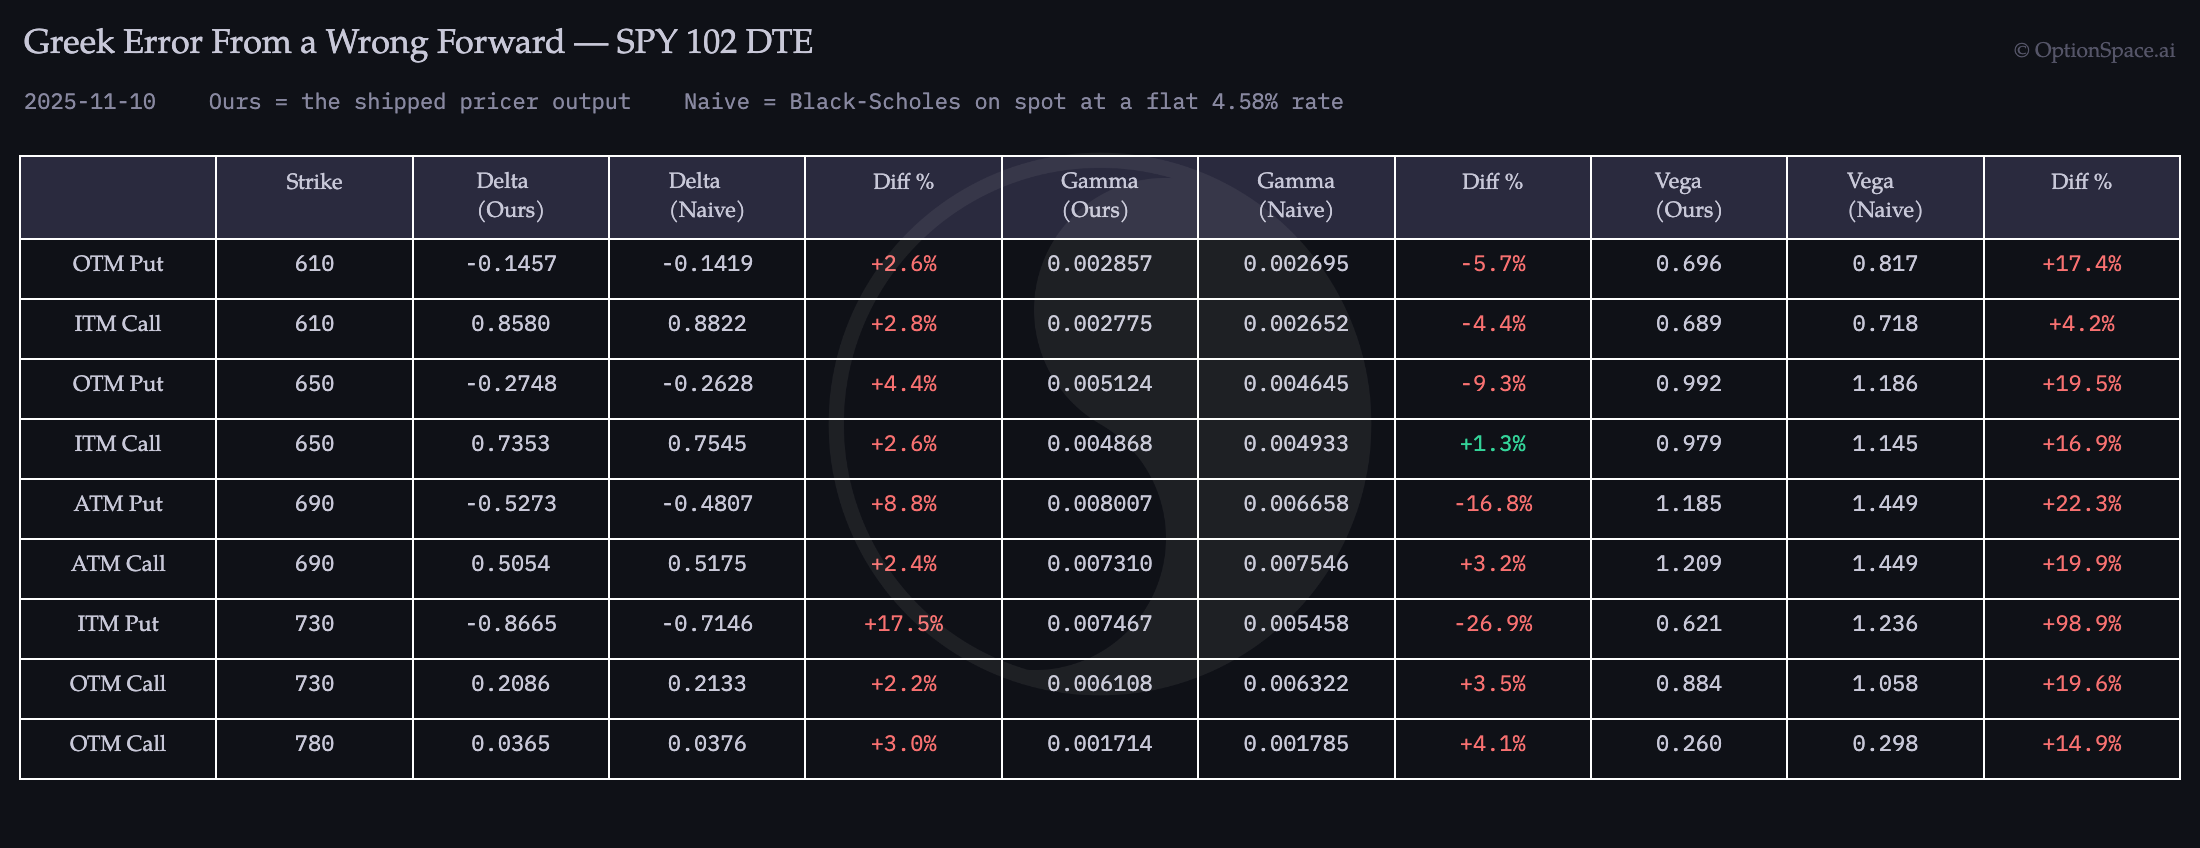
Two diverging curves mean two different sets of greeks at every strike. Delta, gamma, and vega are all derived from the fitted surface; if the call curve and put curve disagree, your greeks depend on which one you happen to use. The errors are worst for ITM options, where the wrong curve is extrapolated far from its fitted region. Green is agreement within 2%; red is not. “Ours” is the shipped pricer's own output, not a reconstruction.

Greek comparison table for SPY 1 DTE. Delta errors are all under 2 percent and shown green; the in-the-money call's vega is off by 15.2 percent and shown red. Greek comparison table for SPY 1 DTE. Delta errors are all under 2 percent and shown green; the in-the-money call's vega is off by 15.2 percent and shown red.
Fig. 07SPY, 1 day, nine strikes across the board.

1 DTE: Overnight, most of the board still agrees; delta is within 2% everywhere. The exception is the in-the-money call, where vega is off by 15.2% and gamma by 5.4%. Short-dated traders making multiple round trips per day compound these errors.

Greek comparison table for SPY 39 DTE. Delta errors are mostly under two percent and shown green; vega errors run from 10.6 to 54.0 percent and are shown red. Greek comparison table for SPY 39 DTE. Delta errors are mostly under two percent and shown green; vega errors run from 10.6 to 54.0 percent and are shown red.
Fig. 08SPY, 39 days: the dividend expiry.

39 DTE (dividend expiry): Vega is wrong at every strike on the board; 10.6% to 54.0%, all in the same direction, because a wrong forward misplaces the whole surface rather than jittering it. The real damage is on the ITM put: delta off by 9.5%, gamma by 14.5%, vega by 54.0%. If you're trading spreads or hedging a position that crosses the forward, the naive model gives you greeks from two inconsistent surfaces.

Greek comparison table for SPY 102 DTE. The in-the-money put's vega is off by 98.9 percent, its gamma by 26.9 percent and its delta by 17.5 percent, all shown red. Greek comparison table for SPY 102 DTE. The in-the-money put's vega is off by 98.9 percent, its gamma by 26.9 percent and its delta by 17.5 percent, all shown red.
Fig. 09SPY, 102 days. Every diff column is red except one.

102 DTE: ITM put vega error reaches 98.9%; if you think you have $1,000 of vega exposure, you actually have $1,989. That same put's delta is off by 17.5% and its gamma by 26.9%. Even the well-behaved OTM calls carry 15–20% vega error and 2–3% delta error. These aren't rounding errors. They're systematic biases that make your hedge ratios meaningless.

The fix isn't complex. It's about getting the details right.

Four modeling choices underpin these comparisons.

01

Implied Forward

We derive the forward price at each expiry using our American pricer, finding the value where the call and put implied vol curves line up, exactly as shown in the charts above.

02

Implied Rates

Instead of using a flat SOFR rate, we imply a full rate term structure from SPX put-call parity. The rate at 30 days can differ from the rate at 180 days by 40+ basis points.

03

Discrete Dividends

We model each dividend as a discrete cash payment at its ex-date, not a continuous yield. This matters for short-dated options near a dividend, exactly where the naive approach fails worst.

04

Settlement Lag

Pricing an option requires correct accounting of when cashflows settle. Options settle T+1, stocks have settled T+3, T+2, and now T+1 over the years. Not accounting for this impacts short-dated option pricing, exactly where most trading happens.

Precision isn't a feature. It's the foundation.

Every tool in OptionSpace, including vol surfaces, signals, backtests and earnings analysis, is built on a pricing layer that gets the math right. That's not a technical detail. It's the difference between analysis you can trust and analysis that looks plausible.